SME IPO Underwriting and Market Making: Roles, Commitments and Key Thresholds
Reviewed on: 4 October 2026. Reviewed by Abhipra RTA Team.
SME IPO underwriting and market making are separate arrangements. Under SEBI’s current ICDR Regulations, the full offer must be underwritten, with the lead manager(s) taking at least 15% of the issue size on their own account(s). Separately, the issuer appoints an SME exchange stock broker for compulsory market making, with initial inventory of at least 5% of the specified securities proposed to be listed and a minimum three-year period.
What underwriting covers in an SME IPO
Underwriting is a commitment to subscribe to the part of an issue that remains unsubscribed, subject to the applicable agreements and regulations. Regulation 260 of the SEBI (Issue of Capital and Disclosure Requirements) Regulations, 2018 (ICDR) requires the initial public offer to be 100% underwritten. The underwriting cannot be limited only to a minimum-subscription threshold.
The issuer, in consultation with its lead manager(s), appoints merchant bankers or stock brokers registered with SEBI as underwriters. Lead manager(s) must underwrite at least 15% of the issue size on their own account(s). That 15% is included within the total 100%; it is not an additional 15% on top of the offer and it is not the market maker’s inventory.
One day before the issue opens, the lead manager(s) file an undertaking with SEBI that the offer is fully underwritten, together with the list of underwriters, nominated investors and sub-underwriters and each party’s commitment. Those arrangements must also be disclosed in the offer document. If an underwriter fails to meet its obligation or a nominated investor does not take up the unsubscribed portion, the lead manager(s) must fulfil the underwriting obligation.
What market making does after listing
Regulation 261 requires the lead manager(s) to ensure compulsory market making through stock broker(s) of the SME exchange appointed by the issuer. The minimum period is three years from listing or, where the regulation applies, from migration from the Main Board under Regulation 276.
At allotment, the market maker’s inventory must be at least 5% of the specified securities proposed to be listed on the SME exchange. The offer document must describe the market-making arrangement. Agreements with nominated investors to receive or deliver securities for market making require prior approval of the SME exchange.
The rule also restricts the market maker from buying shares from the issuer’s promoters or promoter group, or from persons who acquired shares from them, during the compulsory market-making period. Regulation 261 also sets out minimum-contract-size handling. Issuers and advisers should confirm the latest exchange operating instructions and the issue-specific arrangement before relying on a particular quoting, inventory or lot-handling process.
Market making is a structured trading arrangement; it does not guarantee a buyer at every moment, a particular price, continuous liquidity, or an investment outcome. Underwriting commitments do not guarantee that an investor will receive an allotment or that the listed shares will perform well.
Reading the thresholds correctly
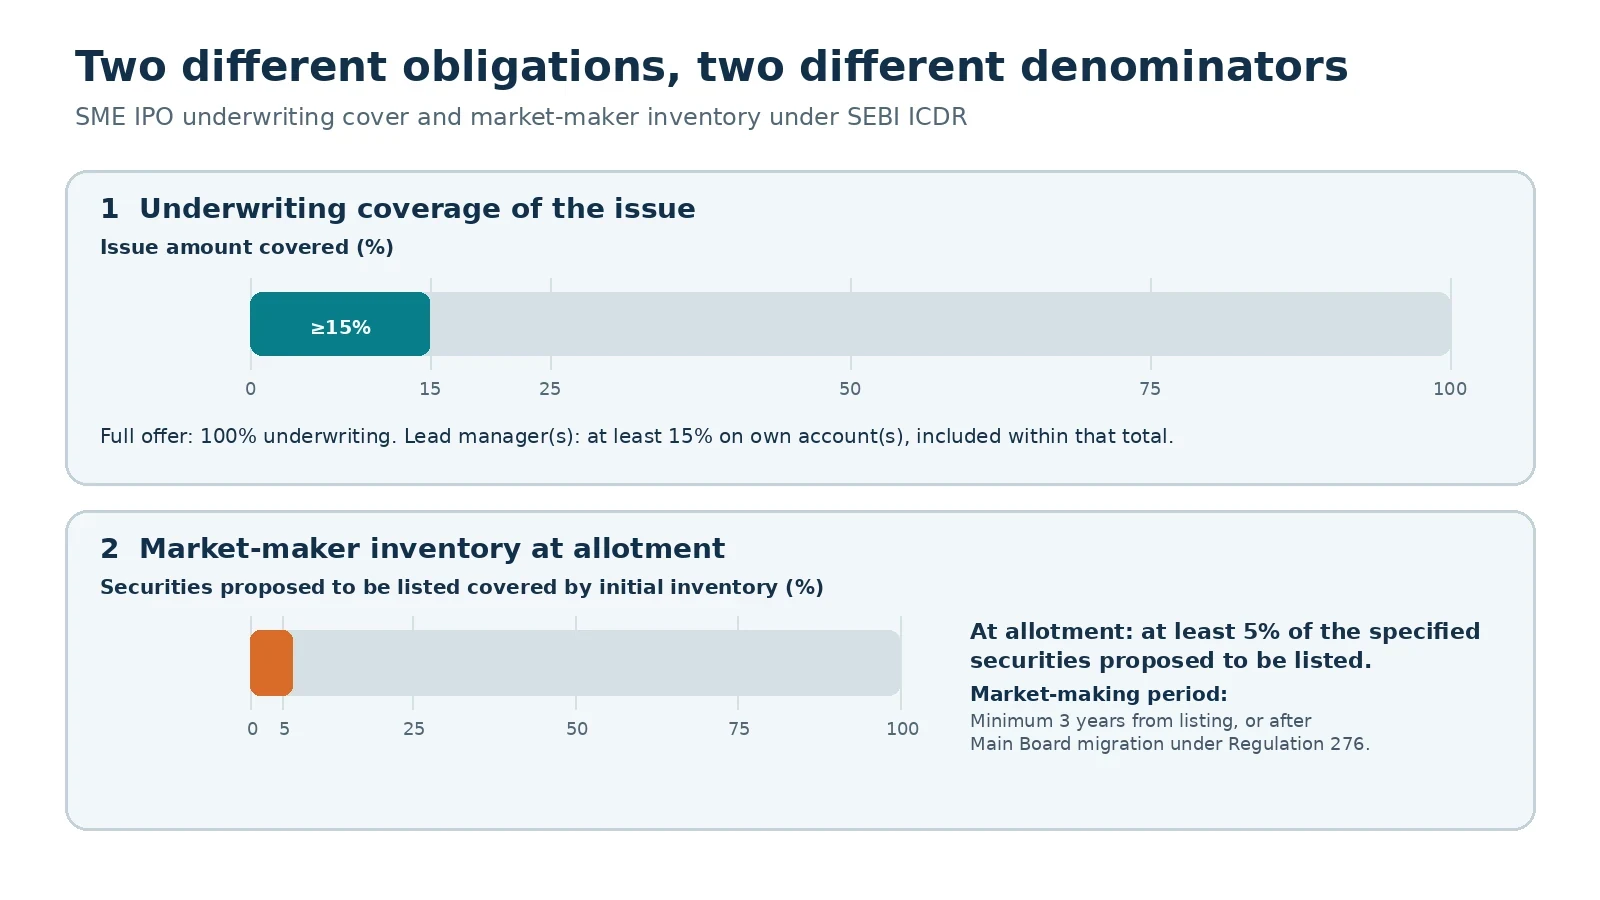
The first horizontal scale is issue amount covered by underwriting, from 0% to 100%. The full offer is covered; the highlighted 15% is the minimum portion the lead manager(s) underwrite on their own account(s), already inside the 100% total.
The second horizontal scale is specified securities proposed to be listed, from 0% to 100%. It measures the market maker’s inventory at allotment; the minimum is 5%. This is a different denominator from the issue amount used for underwriting. The three-year period is a separate time requirement, not a percentage of either amount. The inference is that underwriting allocates subscription risk before allotment, while market making is a post-listing obligation supported by initial inventory.
From issue planning to post-listing duties
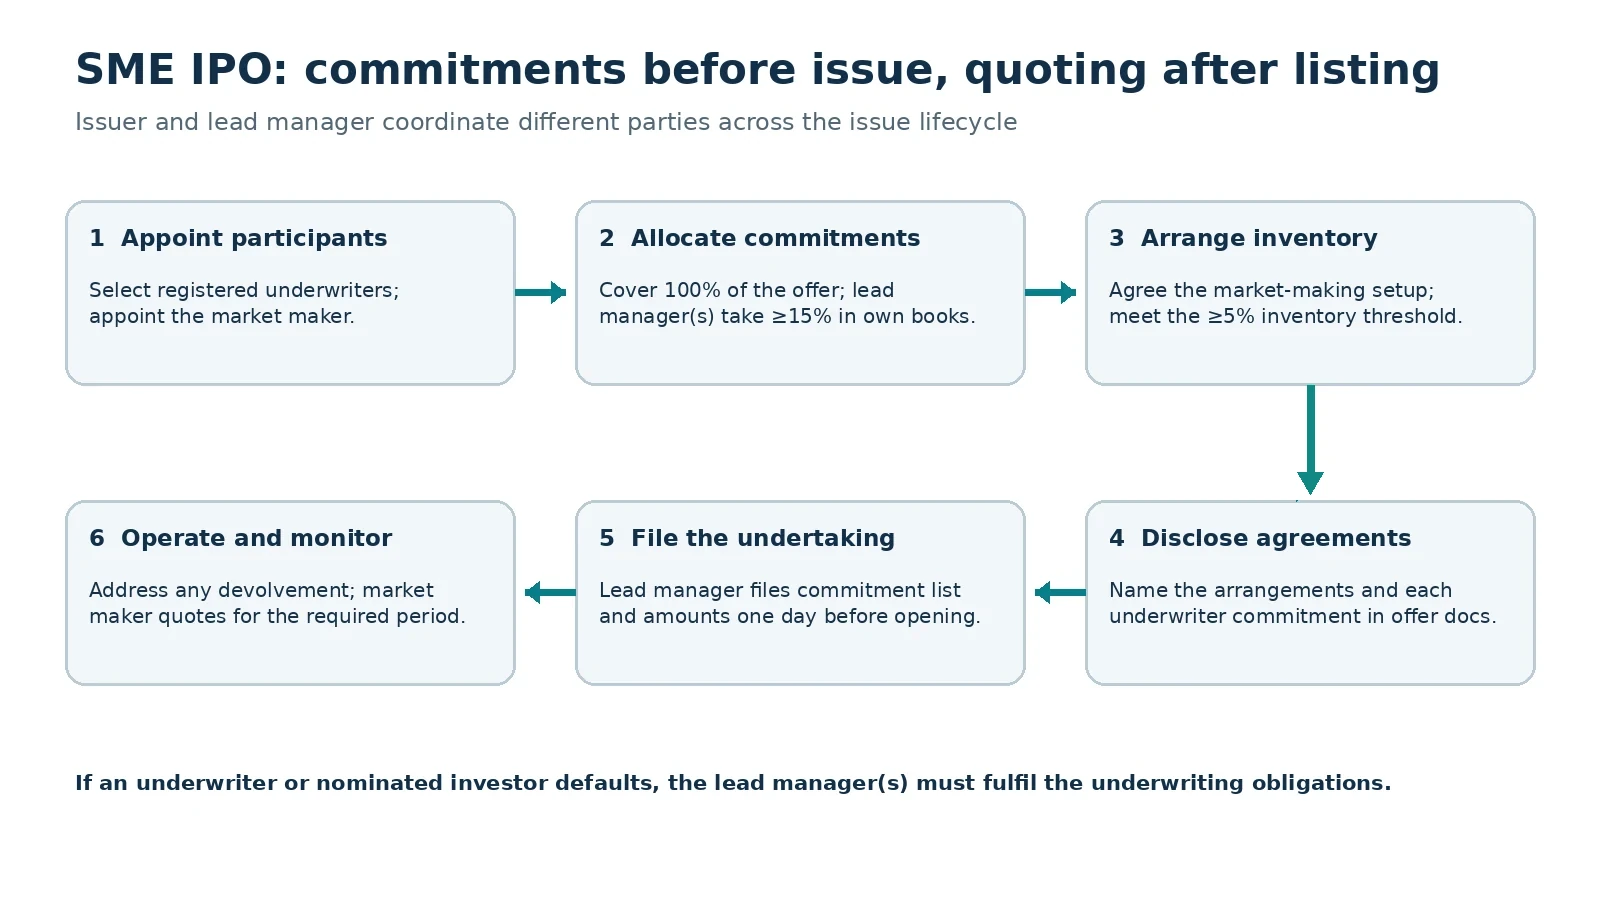
The workflow starts with the issuer and lead manager selecting registered underwriters and appointing an SME exchange market maker. Before the issue opens, the parties document and disclose commitments; the lead manager files the full-underwriting undertaking and commitment list one day before opening. If an underwriter or nominated investor defaults, lead manager(s) fulfil the underwriting obligations. After listing, the market maker carries out its separate obligation for the prescribed period.
Issuer readiness checklist
- Reconcile the offer size and ensure underwriting commitments cover 100% of the offer.
- Allocate the lead manager(s)’ own-account underwriting commitments to at least 15% of issue size, included within the total.
- Appoint SEBI-registered underwriters in consultation with the lead manager(s); document each commitment and any nominated-investor or sub-underwriter role.
- Appoint the SME exchange stock broker market maker and prepare the market-making agreement and initial inventory for the 5% allotment-date threshold.
- Confirm any nominated-investor arrangements and prior SME exchange approval requirements.
- Make the relevant arrangements clear in the offer document and file the lead manager(s)’ undertaking and commitment list one day before issue opening.
- Plan for lead manager(s) to fulfil commitments if an underwriter or nominated investor fails.
- Calendar the three-year market-making period from listing, or applicable Main Board migration, and confirm current exchange procedures.
How Abhipra can assist
Preparing for an SME IPO and need a Registrar-to-an-Issue/RTA workstream? Contact Abhipra RTA Services at rtaservices@abhipra.com, call 011-42390783, or contact +91-9818080700. Share the company name, current company type, proposed listing platform, latest audited financial year, capital structure, shareholder count, existing ISINs and target issue timeline for an initial operational discussion. Eligibility decisions, merchant-banker advice and regulatory approvals remain subject to the applicable framework. Do not send sensitive KYC documents until a secure submission channel is provided.
Source links
- SEBI ICDR Regulations, 2018, consolidated through 21 March 2026, especially Regulations 260 and 261.
- SEBI’s current list of regulations, which lists ICDR as last amended on 21 March 2026.
- SEBI Master Circular for Issue of Capital and Disclosure Requirements, 9 February 2026.
- NSE Emerge requirements and process for the exchange’s issue-stage requirements. Issuers should confirm current exchange instructions for their proposed platform.
Disclaimer
This article is for general educational information and does not constitute legal, investment, tax, transaction or merchant-banking advice. SME IPO eligibility and obligations depend on the issuer, issue structure and applicable SEBI and exchange requirements in force at the relevant time. Underwriting and market making do not assure subscription, allotment, liquidity, price stability or investment returns. Obtain advice from appropriately registered and qualified professionals for a proposed issue.