Personal Accident Insurance: Why It Matters When Income Depends on You
An accident can affect a household in two ways: it can create immediate treatment costs and reduce the income that pays regular bills. Personal accident insurance is designed around accidental events, so the useful question is not “is it cheap?” but “which financial shock does the wording actually address?”
What personal accident insurance is meant to cover
Personal accident cover generally responds to an accidental bodily injury, subject to the policy’s definitions, exclusions and benefit schedule. Depending on the product, benefits may include accidental death, permanent total disablement, permanent partial disablement, temporary total disablement, accident hospitalisation or an education grant. These are distinct benefits; a policy may include only some of them.
IRDAI lists its Guidelines on Standard Personal Accident Insurance Product under reference IRDA/HLT/GDL/MISC/036/02/2021. The standard product is commonly known as Saral Suraksha Bima, but the insurer’s schedule and wording still control the claim. IRDAI guidelines index
It is not a substitute for life insurance, health insurance or an emergency fund. Life insurance addresses death from covered causes; health insurance generally addresses eligible medical expenses; accident insurance addresses specified accidental outcomes. A household may need more than one layer because the risks and triggers differ.
Read the trigger before comparing premiums
An accident policy does not pay merely because an event feels serious. Check the definition of accident, the time limit linking injury to death or disablement, the percentage payable for partial disablement, exclusions and the evidence required. An older IRDAI-hosted policy wording illustrates the structure: an accidental death or disablement benefit can require the injury to be the sole and direct cause and the outcome to occur within 12 calendar months. This is a policy example, not a universal rule. IRDAI-hosted personal accident wording
Ask whether a permanent-total-disablement definition is occupation-based or based on specified physical losses. Ask whether temporary-total-disablement payments are weekly, capped, and subject to medical certification. For partial disablement, the table may pay a percentage of the capital sum insured rather than the entire amount. Read the Customer Information Sheet and policy schedule with the full wording; IRDAI says the information sheet should summarise the type of insurance, sum insured, coverage, exclusions, deductions, renewal and claims information. IRDAI health department consumer information
A simple household cash-gap example
Suppose essential outgoings are ₹60,000 a month and a self-employed household wants to protect six months of cash flow. The planning need is ₹3.6 lakh. If ₹1.2 lakh of liquid savings is reserved for this event, the illustrative shortfall is ₹2.4 lakh. This is a planning example, not a premium quote, claim estimate or recommended sum insured.
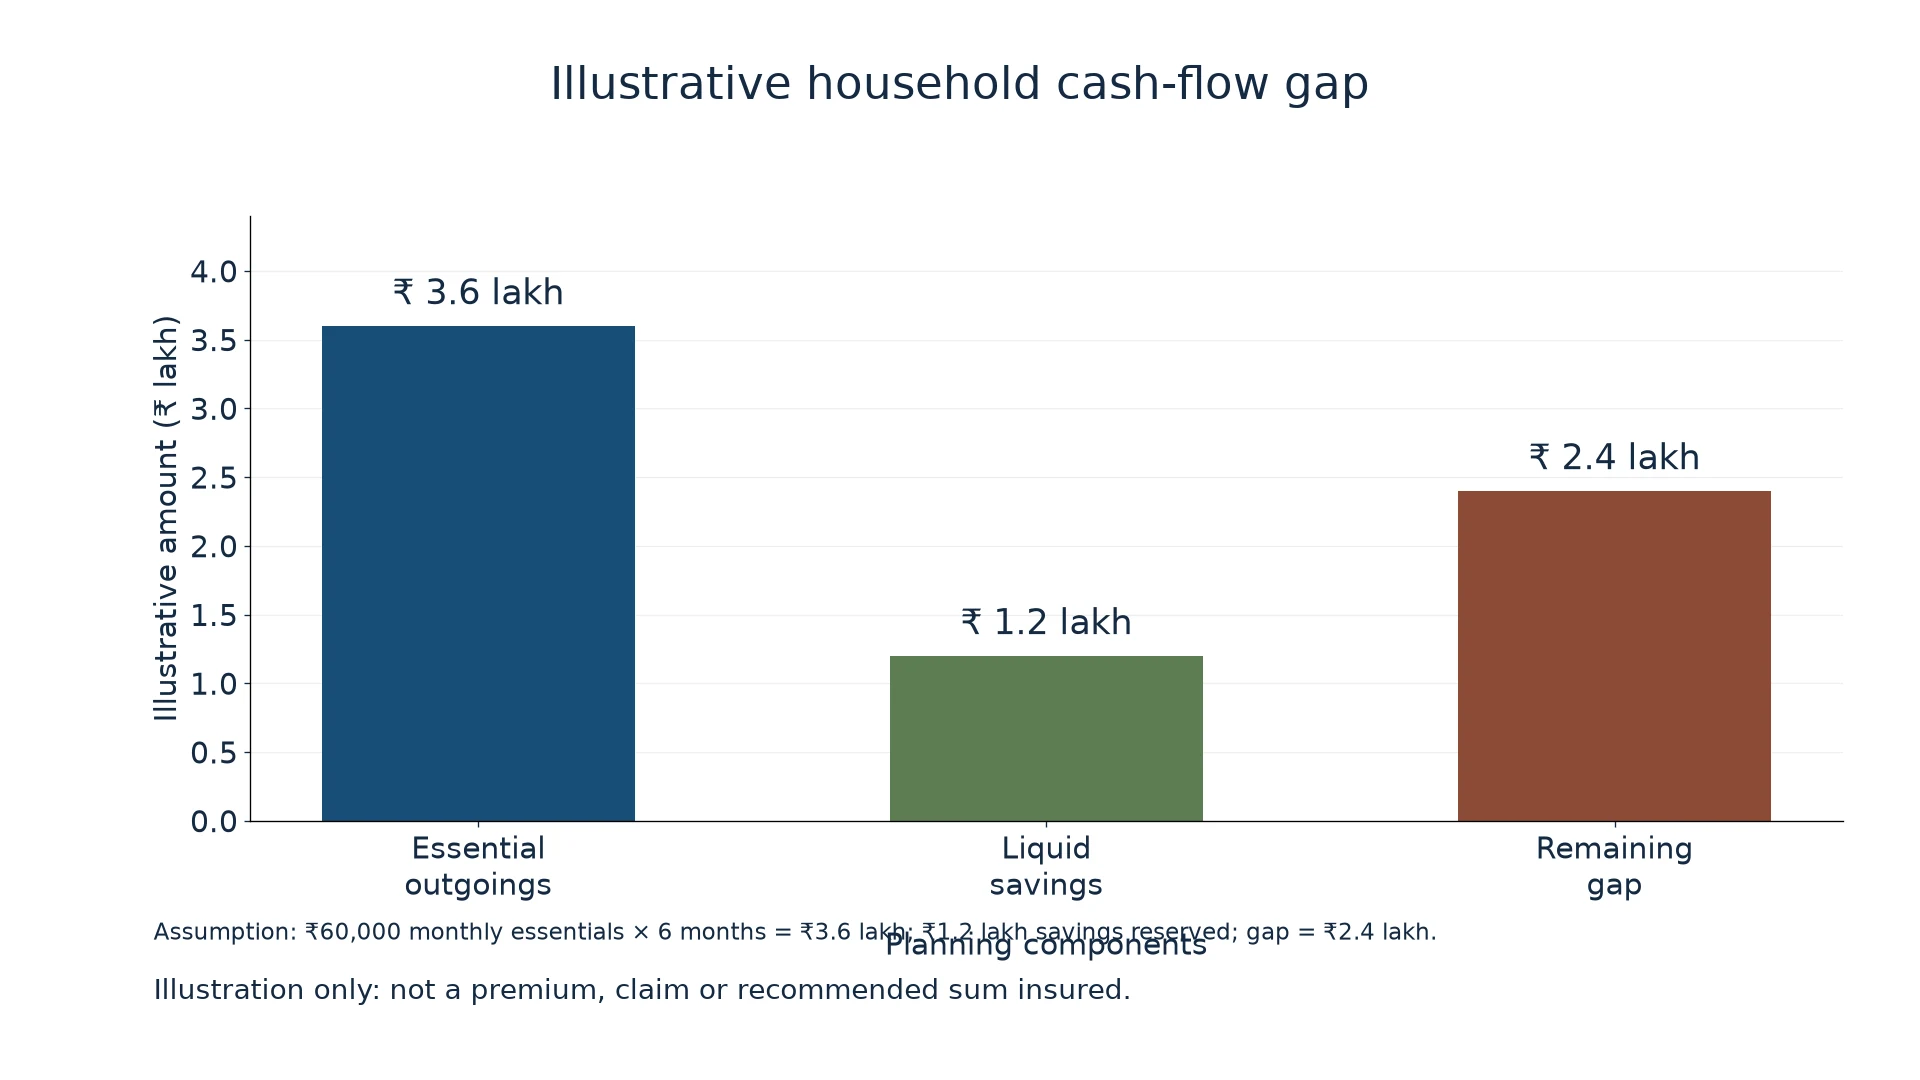
The horizontal axis compares the three planning components: essential outgoings, liquid savings and the remaining gap. The vertical axis shows illustrative rupees in lakh. The inference is that insurance should be considered alongside accessible savings and other cover; it should not be counted twice as both cash already available and future claim proceeds.
What the accident cover layer can and cannot do
The connected scenes show a household moving from identifying a vulnerability to checking the claim conditions. The people and documents are fictional; no customer information appears in the images.
| Layer | Primary question | Typical limitation to check |
|---|---|---|
| Emergency savings | Can essential bills be paid while a claim is assessed? | Liquidity, replenishment and whether the money is actually ring-fenced |
| Health insurance | Which eligible treatment costs may be reimbursed? | Sum insured, exclusions, deductibles, sub-limits and network rules |
| Personal accident cover | What accidental death or disablement benefit is defined? | Accident definition, disablement table, exclusions, evidence and time limits |
| Life insurance | What happens to dependants after death? | Covered cause, nominee details, policy term and claim documentation |
The table is a reading aid, not a recommendation. The same policy can have different outcomes for two people because occupation, benefits selected, exclusions and documentation differ.
Five-step policy review workflow
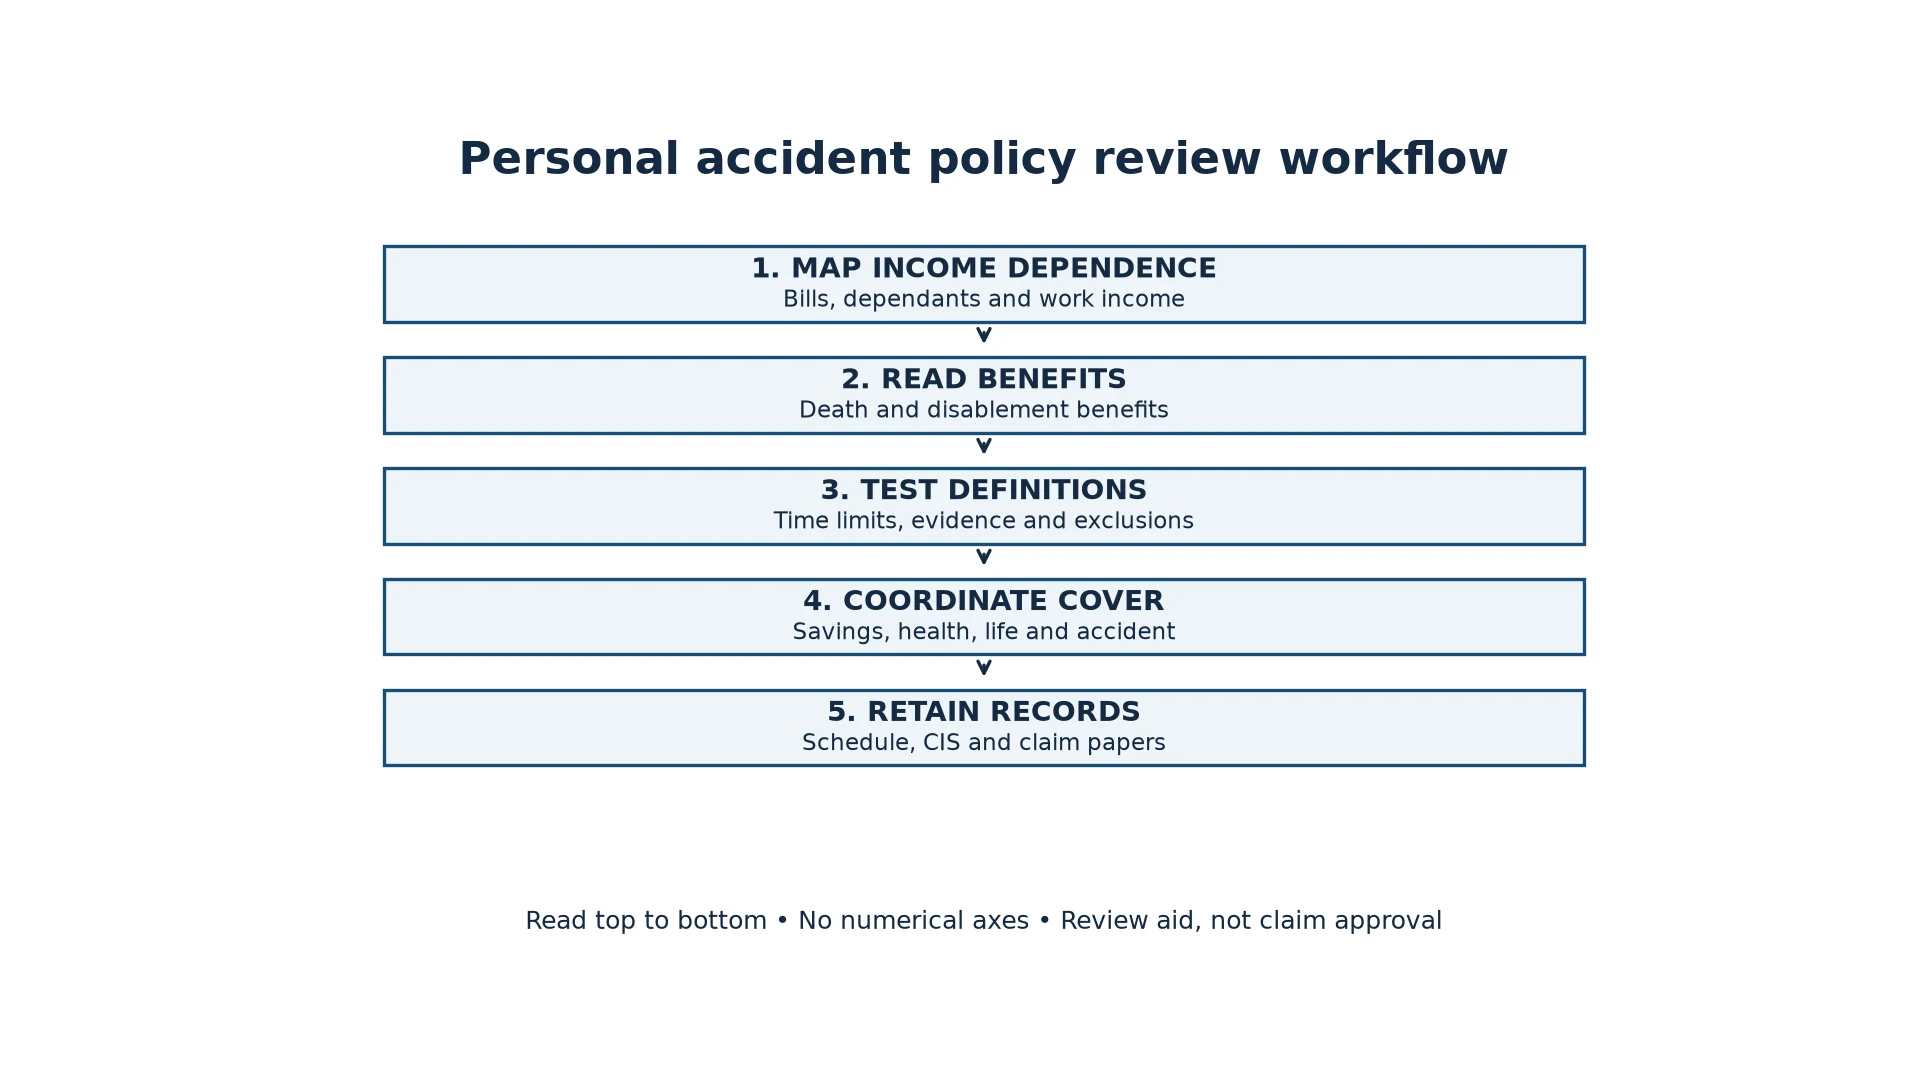
This workflow has no numerical axes. Read it from left to right:
- Map income dependence. List essential monthly outgoings, dependants, debt payments and the work income that could stop.
- Read the benefit table. Identify accidental death, permanent total or partial disablement, temporary disablement and any optional accident hospitalisation benefit.
- Test the definitions. Check time limits, medical evidence, occupation wording, exclusions and whether multiple benefits can be claimed for one accident.
- Coordinate the layers. Avoid assuming accident cover reimburses hospital bills or replaces life cover. Match the policy to the gap that remains after savings and existing insurance.
- Retain claim records. Keep the proposal, schedule, Customer Information Sheet, wording, nominee details, accident report and medical documents. Notify the insurer using the stated channel and timeline.
Common mistakes to avoid
Do not compare only the headline sum insured. Do not assume every disability receives 100% of it. Do not treat natural death or illness as an accident claim. Do not leave nominee details outdated. Do not hide material facts or rely on a verbal promise that is absent from the schedule. If a claim is unresolved, follow the insurer’s grievance route; IRDAI describes the Insurance Ombudsman as an alternative dispute channel after approaching the insurer. IRDAI Ombudsman information
For a suitability discussion, Contact Abhipra. Review the exact policy wording before making a decision.
Source Links
- IRDAI guidelines index: standard personal accident product guideline listing.
- IRDAI-hosted personal accident wording: example definitions, benefit structure and time conditions.
- IRDAI health department consumer information: Customer Information Sheet and policyholder information requirements.
- IRDAI Ombudsman information: grievance escalation information.
Disclaimer
This article is for educational and informational purposes only. It should not be considered investment advice, trading advice, tax advice or insurance advice. Investments in securities market are subject to market risks. Please read all related documents carefully before investing. Past performance is not indicative of future returns. Please consult a qualified financial advisor, tax advisor or insurance advisor before making any financial decision.