NPS Sanchay Through FPOs: What PFRDA’s Latest Clarification Means for Subscribers
PFRDA’s 8 October 2026 clarification connects NPS Sanchay enrolment facilitated through Farmer Producer Organisations (FPOs) with an existing Point of Presence (PoP) incentive framework. The practical takeaway for a subscriber is simple: the Rs. 100 incentive is payable to the PoP, not to the subscriber. Your retirement decision should still begin with suitability, KYC and a clear view of how contributions fit your household cash flow.
What the clarification changes — and what it does not
The clarification says that an eligible NPS Sanchay account opened through an FPO can be counted for the PoP incentive under the linked PFRDA circulars. It also says that the framework remains valid up to 31 March 2027, subject to the stated conditions.
It does not create a cash reward, guaranteed return or special payout for the subscriber. NPS Sanchay remains a market-linked retirement arrangement. A subscriber should make an independent decision after understanding the account, the contribution routine and the exit framework.
| Point in the circular | What it means in practice | What to verify |
|---|---|---|
| Rs. 100 per subscriber incentive | It is payable to eligible PoPs for qualifying enrolments facilitated through FPOs and other listed grass-root pension-agent categories. | Do not treat it as money credited to your NPS account or as a discount on your contribution. |
| NPS Sanchay account | The clarification applies the earlier FPO-linked framework to NPS Sanchay account openings. | Confirm that the channel is authorised and that you receive your PRAN and account confirmation. |
| Existing conditions continue | The circular expressly keeps the linked eligibility, initial-contribution and annual-contribution conditions in place. | Check current scheme conditions before paying; keep every receipt and contribution record. |
A clearer way to use an FPO-led enrolment conversation
An FPO may make a local conversation easier, particularly where pension information is hard to access. But a familiar channel is not a substitute for personal verification. Ask who is acting as the PoP or PoP service provider, how KYC will be completed, and where you will receive your PRAN, acknowledgement and service support.
PFRDA describes NPS Sanchay as a simplified NPS variant for the rural and informal workforce. Current scheme information says an Indian citizen aged 18 to 85 may apply, subject to KYC; the initial contribution is at least Rs. 250 and a later contribution is at least Rs. 10 per transaction. These are entry conditions, not a promise of a pension amount or investment return.
The subscriber check map
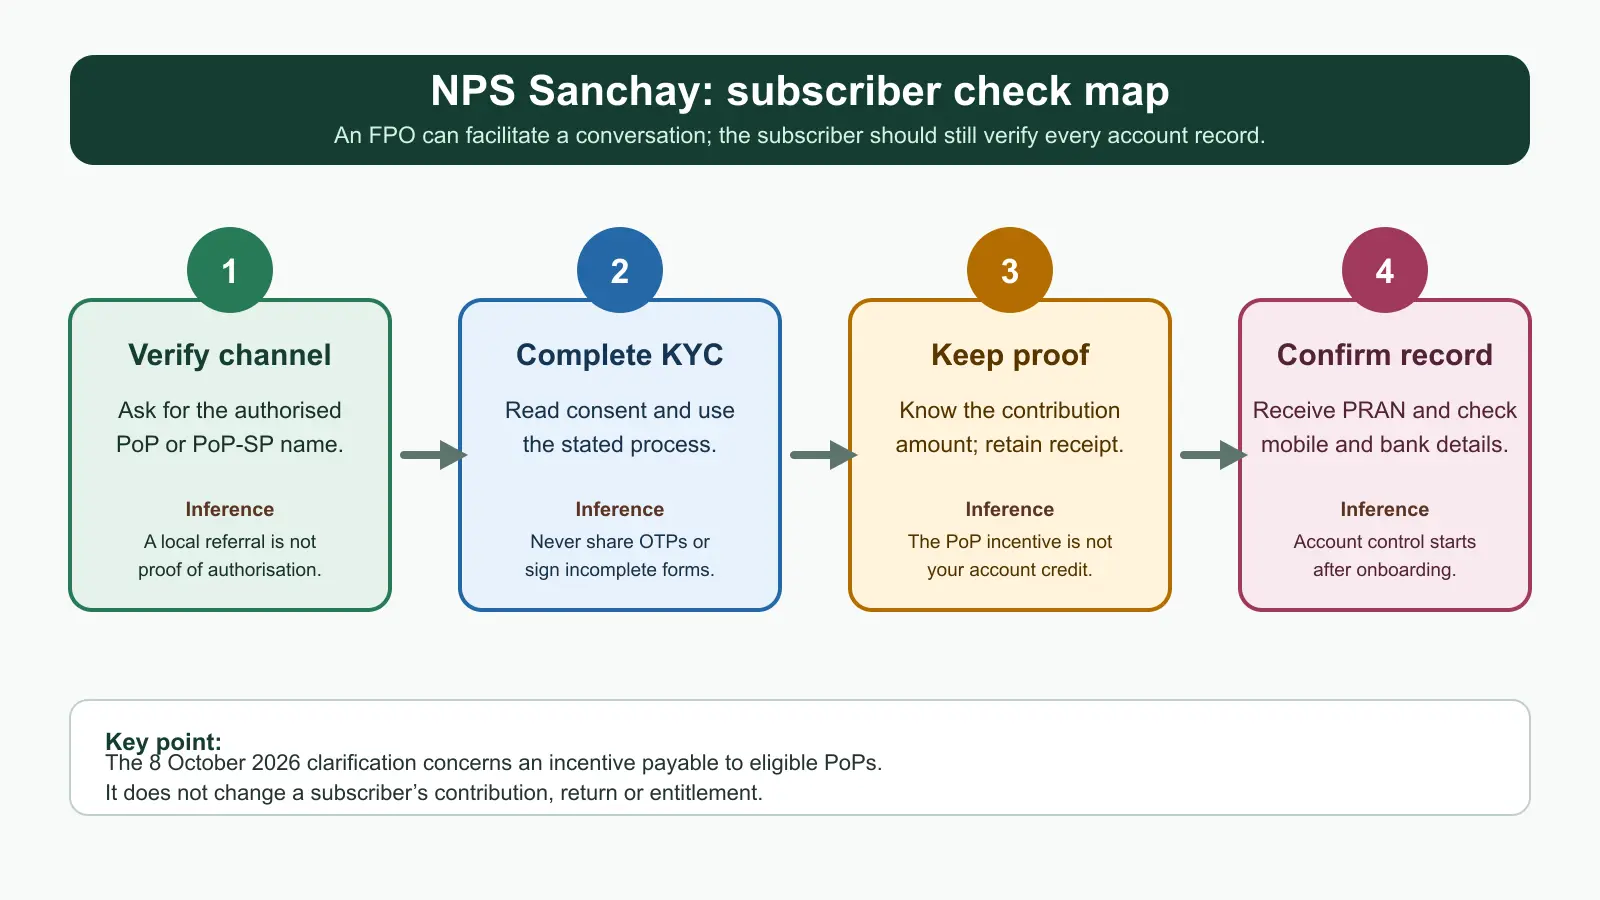
The workflow has no numeric axis because it is a sequence of controls rather than a data comparison. Read it from left to right: first verify the authorised channel; then complete KYC only through the stated route and retain the acknowledgement; next make a contribution only after understanding the amount and receipt; finally verify PRAN and contact details in the account record. The inference is that a local facilitator may assist the process, while account ownership and record-checking remain the subscriber’s responsibility.
Four questions before you contribute
- Is the person or organisation explaining the account connected to an authorised NPS channel, and can they identify the PoP or PoP service provider?
- Have I understood that the PoP incentive is not my contribution, return or benefit?
- Can I keep an emergency fund outside the pension account before committing irregular-income savings to retirement?
- Did I receive and safely retain the PRAN, acknowledgement, contribution receipt and contact-update instructions?
How Abhipra can help
Abhipra has acted as a Point of Presence for 17 years. We can help people understand NPS account-opening steps, KYC readiness, contribution records and servicing requirements before they proceed.
- Learn about Abhipra NPS & Pension services.
- Use Abhipra’s approved NPS account-opening route when you are ready to start.
- Consider Abhipra’s NPS SIP route only after deciding that a recurring contribution is sustainable.
Source links / disclaimer
- PFRDA clarification, 8 October 2026: FPO-facilitated NPS Sanchay enrolment incentive
- PFRDA: NPS Sanchay features, eligibility, contribution and exit information
- PFRDA: introduction of NPS Sanchay, 6 May 2026
This article is for investor education. NPS rules, channel availability, charges, contributions and tax treatment can change. Verify the current official requirements and consider qualified advice before investing.