NPS Retirement Income Schemes and Drawdown: Four Questions Before You Decide
Retirement planning changes character when contributions stop and income needs begin. PFRDA introduced a framework for Retirement Income Schemes and drawdown options under NPS in May 2026. The framework creates more reason to prepare the income conversation before submitting an exit-related request; it does not make one income pattern suitable for every subscriber.
Start with income needs, not a product label
List the expenses that must be met from retirement income, then note other dependable income sources, healthcare needs, family commitments and liquid savings. This turns a broad question about retirement into a cash-flow discussion. A regular income feature and a drawdown feature can serve different needs; neither removes market, longevity or liquidity risk.
NPS is market-linked. A recent account value or past return is not a promise of future income. The more useful starting point is whether a proposed route supports the household's expected spending pattern and risk capacity.
Use a four-stage decision sequence
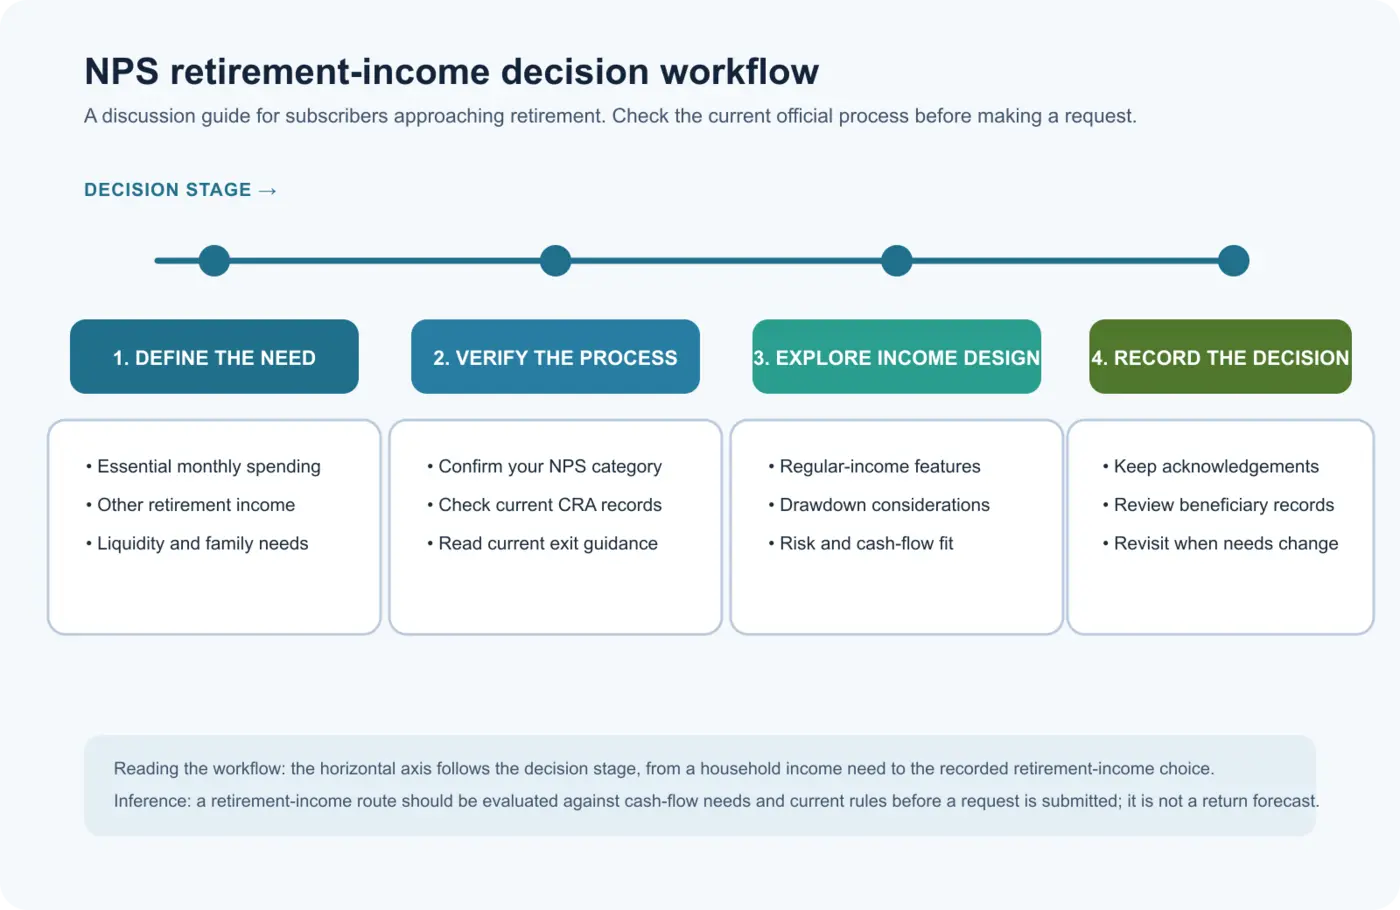
The horizontal axis is the decision stage: define the need, verify the process, explore income design, then record the decision. Each box describes a question rather than a product recommendation. The inference is that a retirement-income route should be assessed against current rules and household cash flow before a request is filed; the workflow does not forecast returns or pension amounts.
1. Define the need
- Separate essential spending from discretionary spending.
- Note income that may continue from employment, rental assets, pensions or other investments.
- Keep an emergency reserve and foreseeable family commitments in the conversation.
2. Verify the current NPS process
- Check the subscriber category, CRA records, bank details and nomination before beginning an exit-related process.
- Read the current PFRDA and CRA guidance because eligibility, documentation and operational steps can change.
- Keep acknowledgement numbers and copies of requests in one secure place.
3. Explore the income design
- Ask how the current Retirement Income Scheme and drawdown options apply to your subscriber category and stage.
- Compare regularity of income, flexibility, residual liquidity and the risks you would retain.
- Treat any illustration as an assumption-based example, not an assurance of income or return.
4. Record the decision and review it
- Keep the confirmation, relevant CRA records and beneficiary details together.
- Review the plan if health needs, household expenses, dependants or other retirement income change.
- Use a qualified adviser for suitability questions and the official process for final instructions.
How Abhipra can help
Abhipra has acted as a Point of Presence for 17 years. We can help subscribers understand NPS service steps and locate the relevant official process before they act. Visit Abhipra NPS and pension services for NPS support. If you are still building the retirement corpus rather than planning retirement income, use Abhipra's NPS account-opening route to begin through Abhipra.
Source links and disclaimer
- PFRDA: Retirement Income Schemes and Drawdown options under NPS
- PFRDA circular PDF, 15 May 2026
- PFRDA active circulars
- NPS Trust overview
This article is for investor education. Retirement-income decisions can have long-term consequences. Verify the current rules, assess tax and cash-flow implications with appropriate professionals, and evaluate suitability before acting.