NPS PRIDE–DISHA: A Better Way to Compare Pension Fund Choices
A pension fund’s latest return can catch your eye, but it may not show what a subscriber who contributes every month actually experienced. PFRDA’s NPS PRIDE–DISHA tool offers a historical, contribution-aware way to compare NPS investment choices.
What PRIDE–DISHA compares
PRIDE–DISHA uses historical NPS scheme Net Asset Values (NAVs) and the Extended Internal Rate of Return (XIRR) method. XIRR can reflect the timing and amount of periodic contributions, so the comparison can be closer to a regular contributor’s experience than a single point-to-point return figure.
The tool lets a subscriber enter details such as date of birth, contribution start date and monthly contribution, then compare investment choices. PFRDA’s July 2026 circular describes support for Composite Schemes, Active Choice and Auto Choice, comparison among funds that operated during the selected period, and results presented in a bar graph. The live tool is the best place to confirm its current inputs and available options.
A simple way to use the comparison
Start with your own NPS context: the account or sector, the period you want to examine, contribution pattern and investment choice. Then compare like with like. If one option uses a different asset allocation or comparison period, its result may not answer the same question.
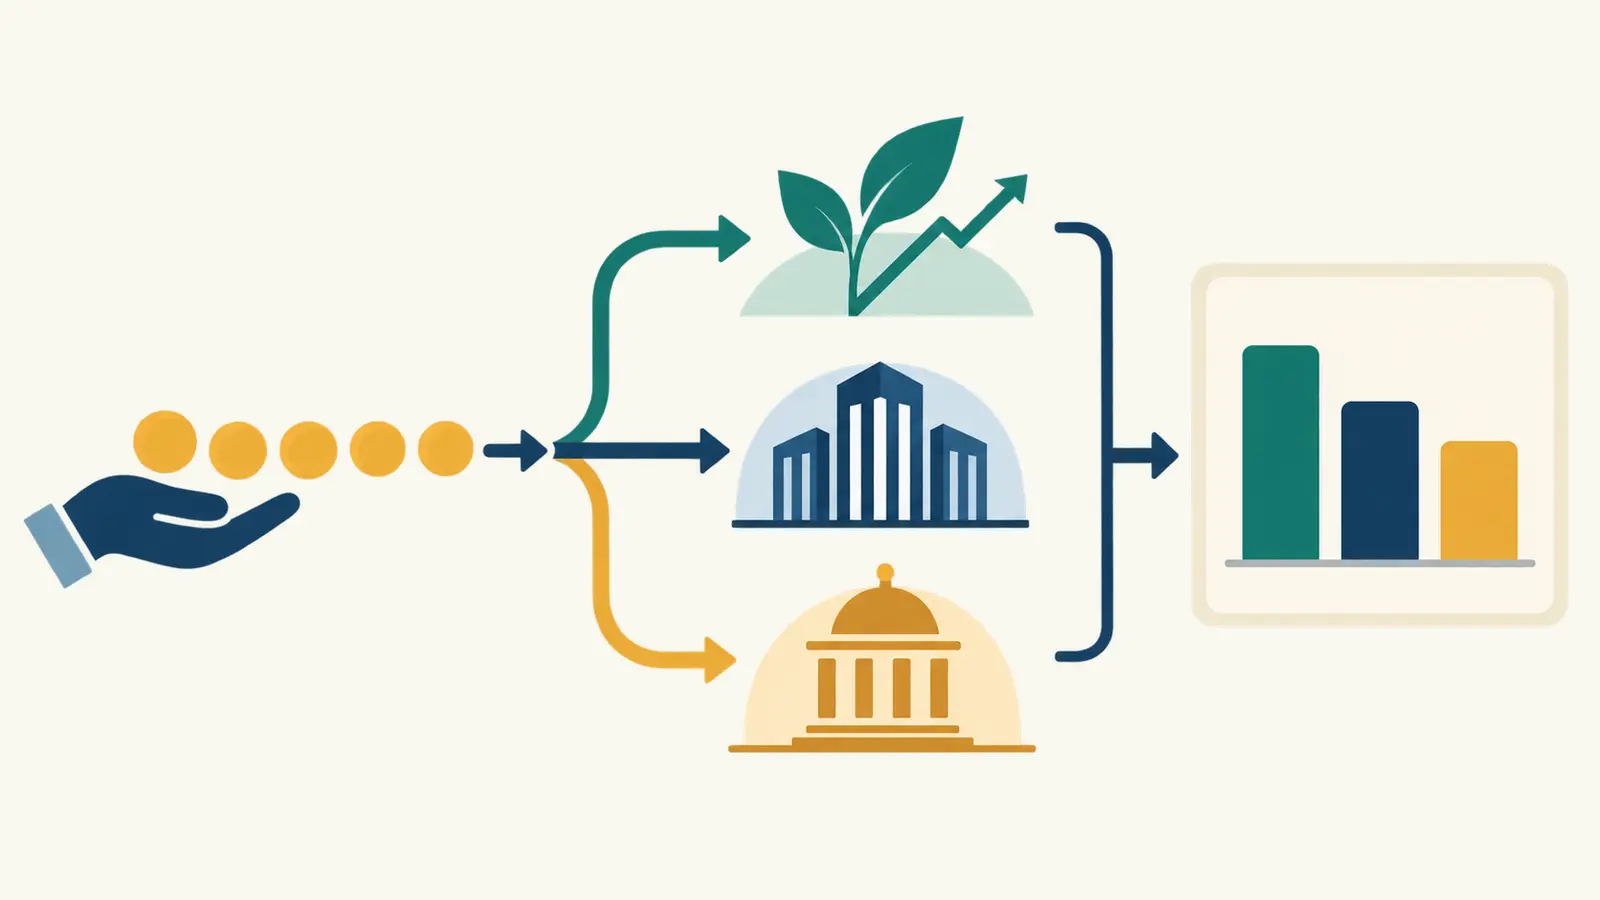
In the tool’s bar graph, read the option labels and the period or measure shown on the screen before comparing bar lengths. The bars are historical comparison outputs: the bar height indicates the displayed result for each selected option. The inference is limited to those inputs and that historical period; it is not a forecast or a promise of future returns.
What to keep in mind before switching
- Past results can differ from future results. PFRDA says the tool uses historical data and does not provide future projections or assumption-based estimates.
- Check the investment mix. Equity, corporate debt and government securities behave differently. Compare choices with similar allocations where possible, and consider whether the risk fits your time horizon and comfort.
- Avoid choosing from one number alone. Review the period, contribution assumptions, scheme choice and fund availability during that period. A historical comparison is one input for a decision, not a complete suitability assessment.
- Follow your account’s process. Before making a change, confirm the current rules, available choices and switching process with your CRA, employer or Point of Presence, as applicable.
Where to access it
Use the official NPS PRIDE–DISHA comparison tool. PFRDA’s 14 July 2026 circular introducing PRIDE–DISHA explains its methodology, scope and limitations. The circular also says additional features, including Tier II, MSF and NPS Vatsalya comparisons and rolling or trailing returns, were on the roadmap; check the live tool for what is currently available.
For help with NPS services, see Abhipra’s NPS & Pension services. Abhipra has acted as a Point of Presence for 17 years.
Frequently asked questions
Does PRIDE–DISHA predict my retirement corpus?
No. It compares historical performance using the details entered. It does not forecast future returns or guarantee an outcome.
Why can XIRR be more useful than a point-to-point return?
When contributions happen at different dates, XIRR accounts for the timing of cash flows. A point-to-point return is a snapshot between two dates and may not represent a subscriber’s periodic contribution experience.
Should I switch to the option with the tallest bar?
Not automatically. First check the comparison period, investment choice and asset allocation. Then consider risk, your circumstances and the applicable switching process. Historical performance alone does not establish that a choice is right for you.
A comparison tool, not a decision-maker
PRIDE–DISHA can make historical comparisons more relevant to a subscriber’s contribution pattern. Use the result to ask better questions about time period, investment mix and risk. Your selection should still reflect your retirement horizon and circumstances, and should not rely on past returns alone.
This article is for investor education and is not investment, tax or legal advice. NPS is market-linked; returns are not guaranteed. Verify current scheme features and rules with PFRDA, your CRA or the relevant NPS intermediary before acting.