NPS e-shramik for Platform Workers: Four Checks Before You Enrol
PFRDA has extended the NPS e-shramik (Platform Service Partner) incentive framework for FY 2026–27. The model is intended to make pension access easier for platform service partners, including gig workers. It does not turn an app notification into a pension promise: enrolment, contributions, investment risk and account records still deserve your own attention.
What the model does
The original NPS e-shramik framework defines a platform service partner as an individual, including a gig worker, who provides services through a platform aggregator under a contract for service. The platform can help the Point of Presence (PoP) facilitate onboarding, but the PoP remains responsible for compliance for partners onboarded through the platform.
The framework permits three contribution arrangements: a joint contribution by the platform and service partner, a service-partner-only contribution, or a platform-only contribution. It does not set a regulatory minimum or maximum contribution threshold for the model, although a platform or partner may set a minimum per credit. Before you opt in, ask who will pay, how often a credit is expected, and whether the arrangement fits your variable income.
The contribution arrangements at a glance
The horizontal axis in this chart lists the three arrangements permitted by the framework. The vertical axis is a count of permitted arrangements, so each bar equals one. It is not a comparison of contribution amounts, charges, returns or pension outcomes.
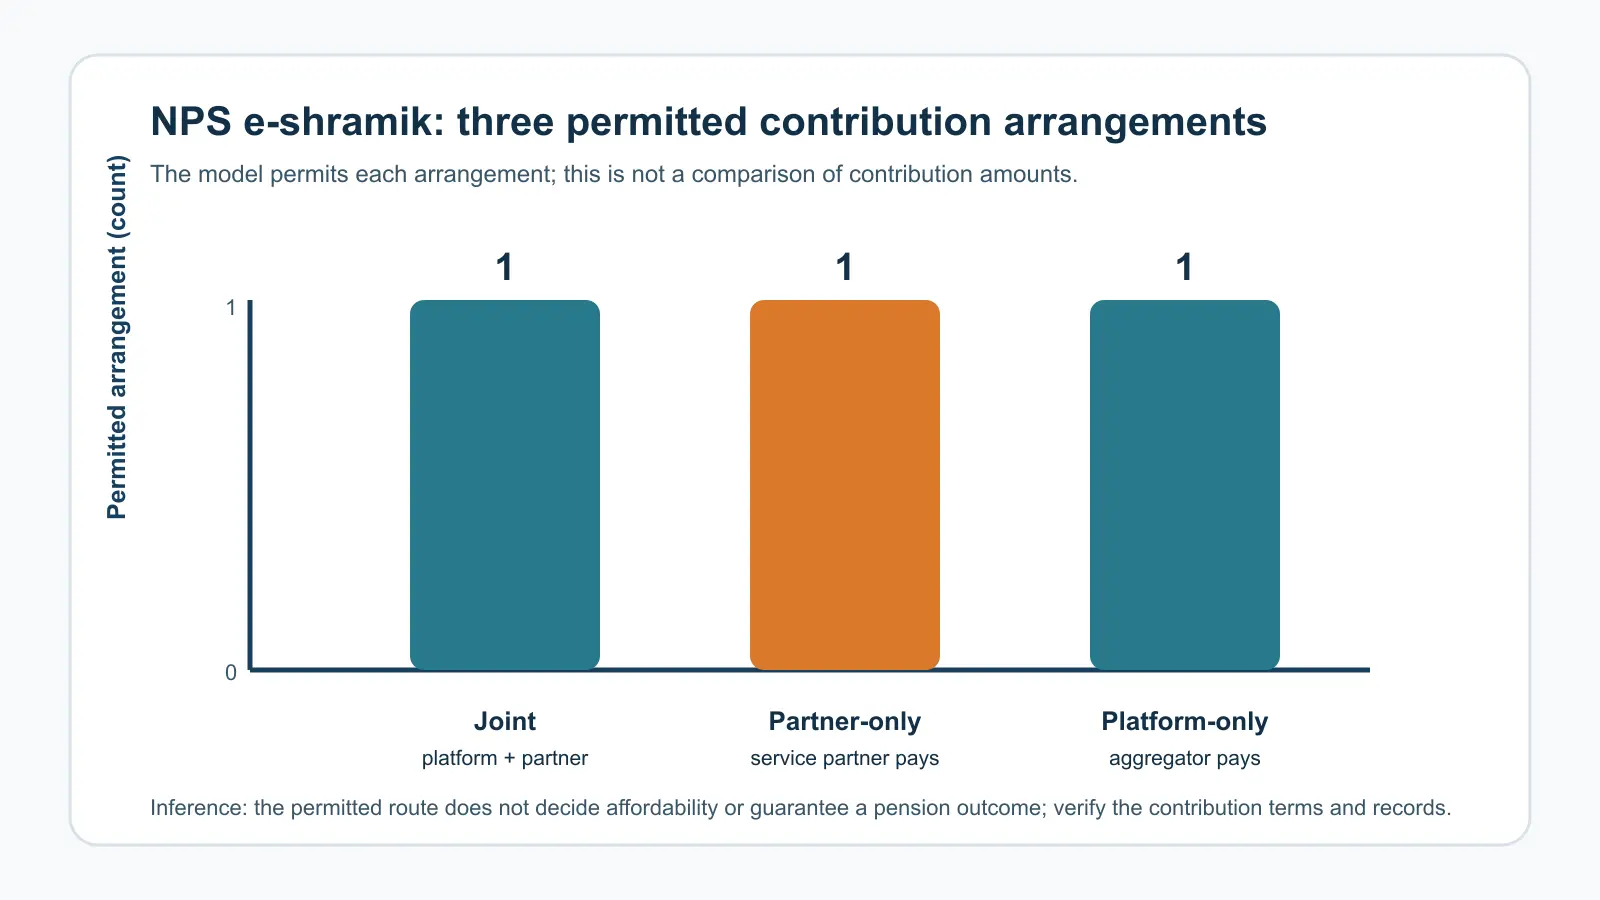
The practical inference is simple: the route by which money is credited does not decide whether the contribution is affordable or suitable. Treat it as retirement money only after covering essential living costs, debt obligations and a cash buffer for income gaps.
Four subscriber checks
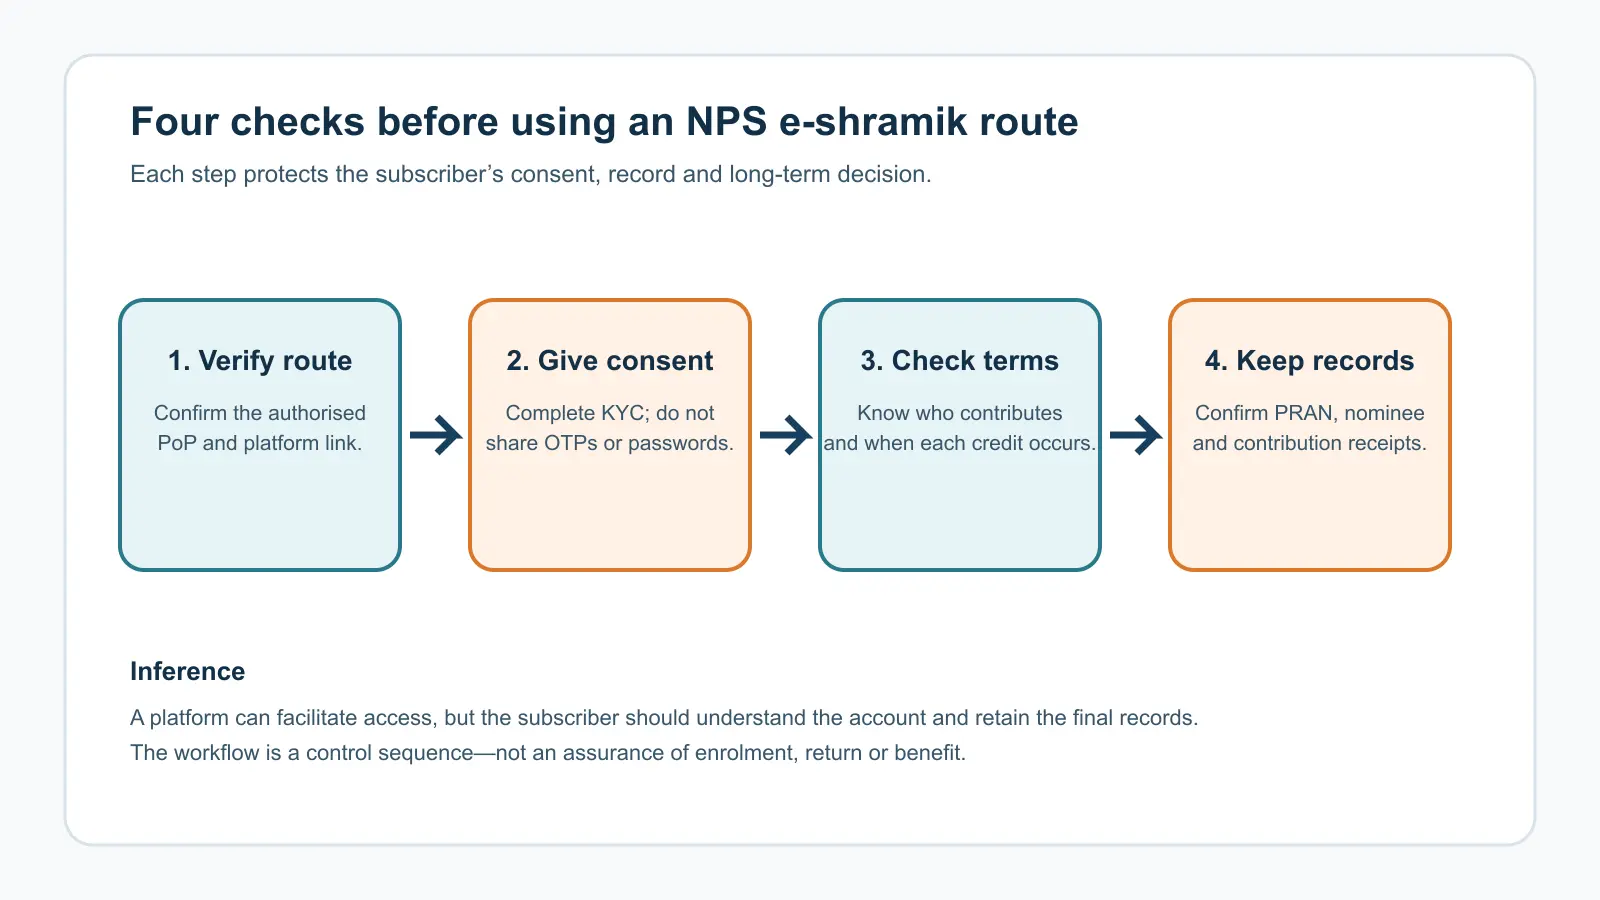
- Verify the route. Confirm the authorised PoP and the platform relationship. Do not rely only on an unsolicited message or an unfamiliar payment link.
- Give informed consent. The first phase can generate a PRAN using KYC particulars and your consent. Never share an OTP, password or device-control access with a caller or chat contact.
- Check the contribution terms. Confirm whether the contribution is joint, partner-only or platform-only; its frequency; and how you will see each credit. NPS remains market-linked, so a contribution is not a guaranteed return or pension amount.
- Complete and retain records. The framework calls for further details including nominee information after initial onboarding. Keep the PRAN, acknowledgement and contribution records, then review them through the authorised account channel.
The workflow is a sequence of controls, not a promise of automatic enrolment or a specific financial result. A worker may work with several platforms, but the original framework says an individual pension account can be opened through one platform aggregator only; it also provides for portability between platform aggregators and to a Common Scheme, subject to the applicable process.
What the incentive extension does not mean
The framework’s incentive is for eligible PoPs, subject to the circular’s conditions; it is not money added to a subscriber’s pension account, contribution or investment return. Do not accept a claim that you must enrol immediately to receive a guaranteed benefit. Check the current circular, contribution record and charges before acting.
How Abhipra can help
Abhipra has acted as a Point of Presence for 17 years. Start with Abhipra NPS & Pension services for account and servicing guidance. If an individual NPS account is suitable after you assess cash flow and risk, use Abhipra’s approved NPS account-opening route. A recurring contribution can be explored through Abhipra’s approved NPS SIP route only when it is sustainable.
Source links / disclaimer
- PFRDA: NPS e-shramik Platform Service Partner Model, 29 October 2025
- PFRDA active circulars: FY 2026–27 incentive-framework extension
This article is for investor education, not investment, tax, legal or employment advice. NPS is market-linked and applicable processes, charges and rules can change. Verify current official requirements and consider your cash flow, goals and risk tolerance before enrolling.