NPS Central: What the New Digital Access Point Means for Subscribers
New pension-service portals can make routine account work easier, but convenience should not replace record checks. At NPS Diwas 2026, PFRDA’s programme listed the launch of NPS Central. Public reporting described it as a unified digital portal bringing together the three Central Recordkeeping Agencies (CRAs). Treat any new channel as an additional way to view or service an account—not as a reason to skip verification.
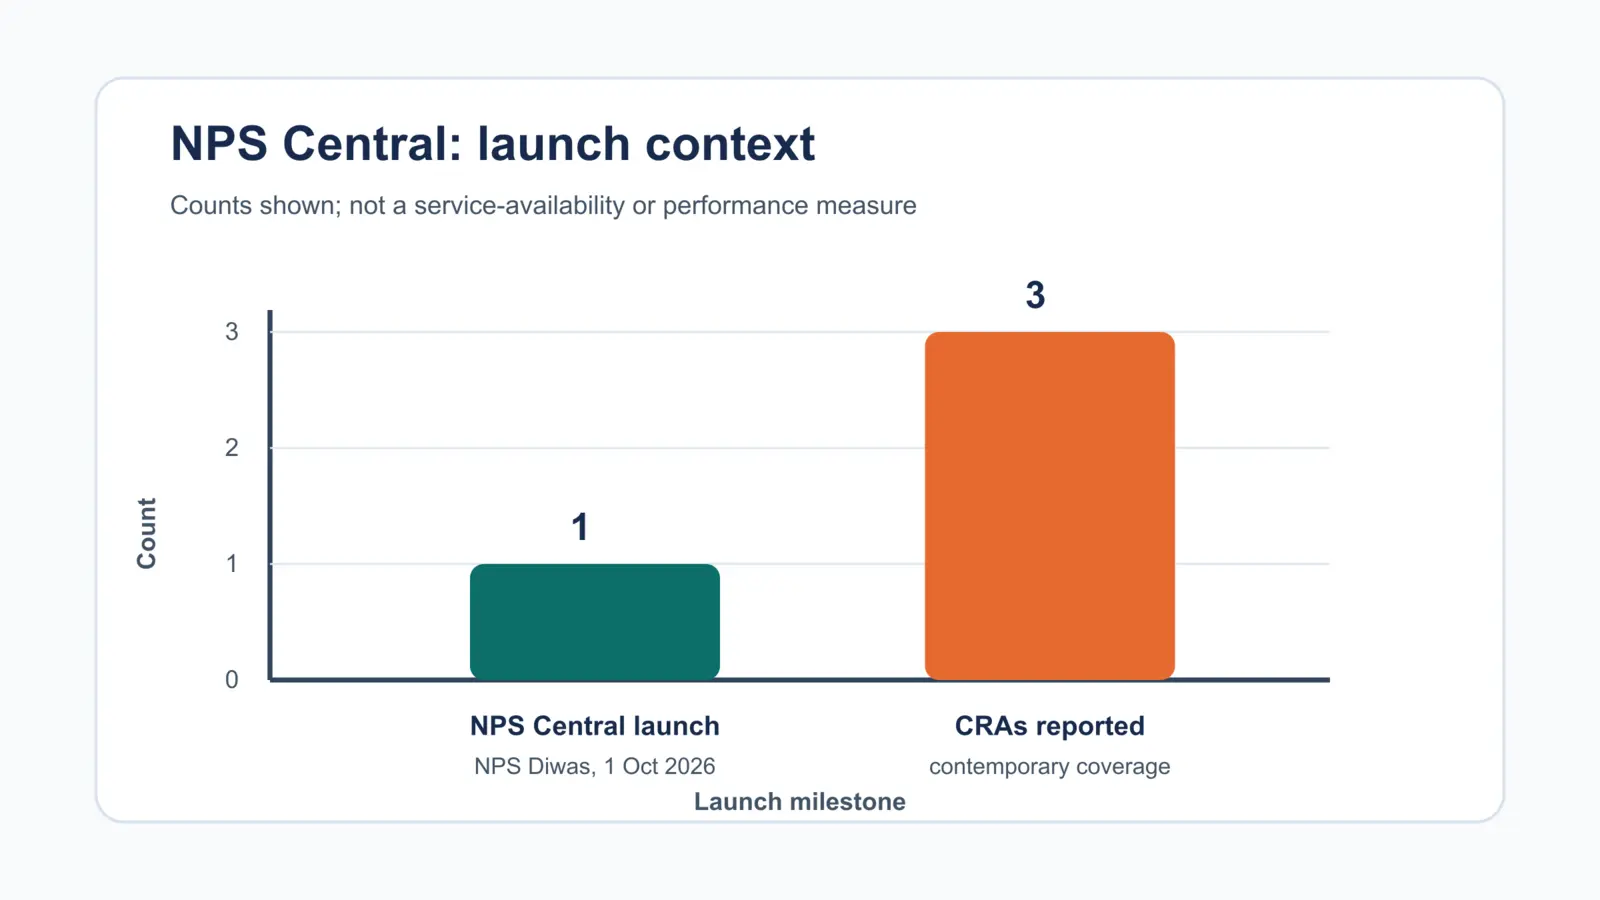
The launch in context
The chart records two verifiable launch facts. The horizontal axis shows the milestone category; the vertical axis is a count. One NPS Central launch was included in the 1 October 2026 NPS Diwas programme. Contemporary reporting described three CRAs being brought into the unified portal. A count of three does not mean that every task, scheme or account record will appear identically; subscribers should check the service available for their own PRAN.
What to check before you use a new NPS service route
- Start from a verified official link. Type the address yourself or begin at the PFRDA, CRA or Abhipra website. Do not follow a link in an unexpected SMS, email or social-media message.
- Confirm the page uses HTTPS and that the domain is exactly the one you intended to reach. A similar-looking name is not evidence of an authorised portal.
- Never share an OTP, password, PRAN login credential or device-control access with a caller or chat contact. An account-service request should not require this disclosure.
- After a contribution, profile change or nomination update, keep the acknowledgement and reconcile it with the transaction statement or account view when it becomes available.
- If a screen, payment request or account detail looks unfamiliar, stop and obtain help through an official service channel before proceeding.
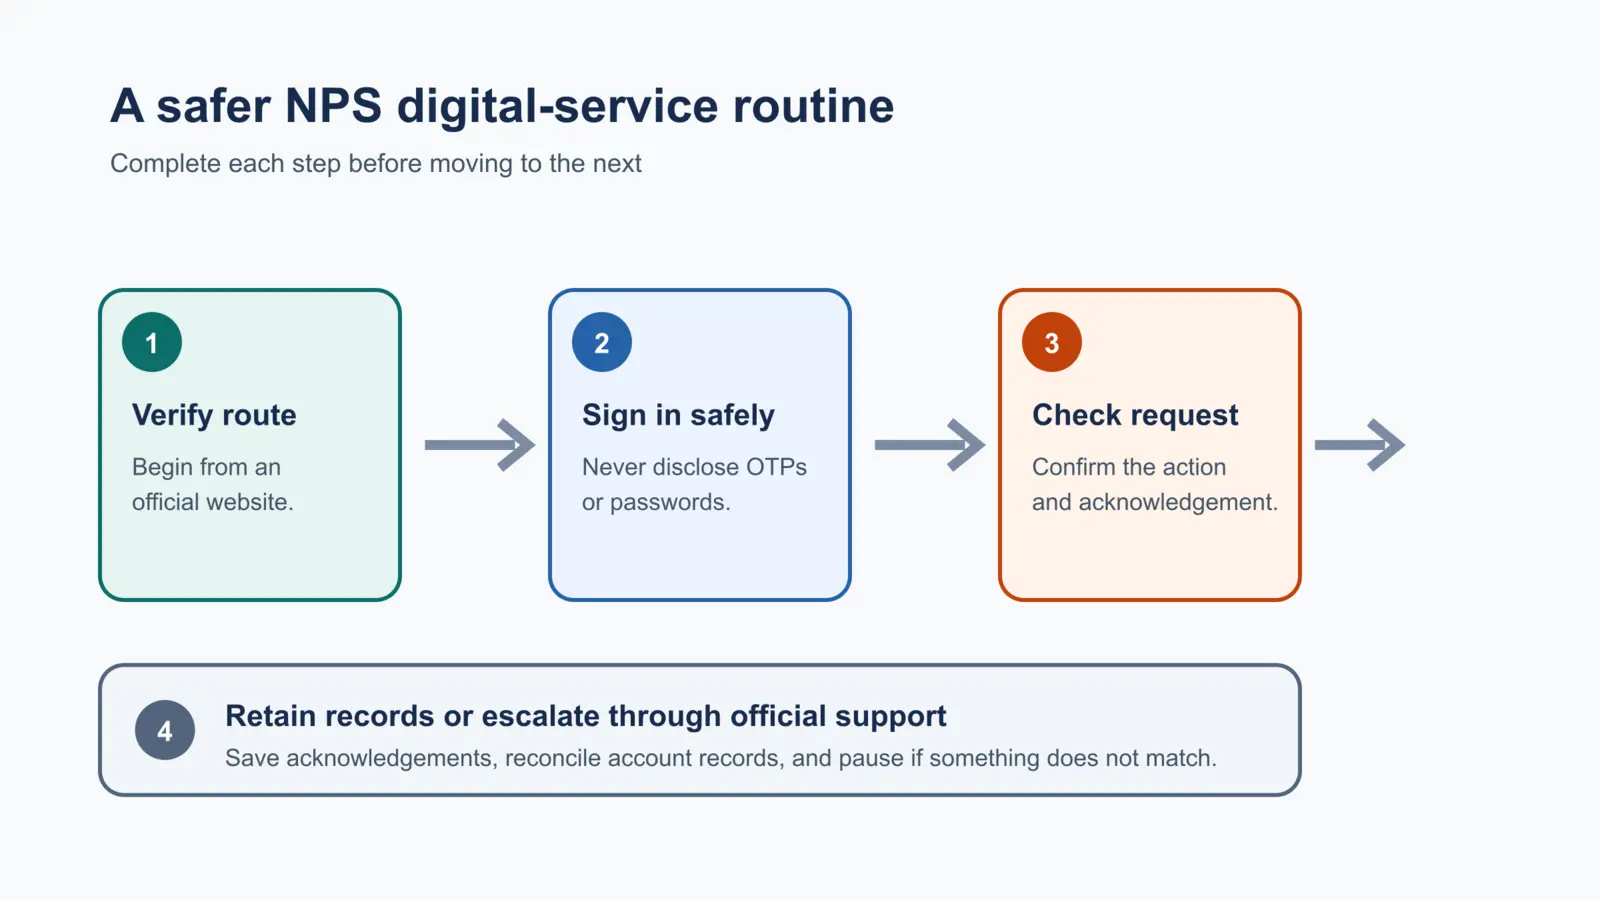
A four-step account-control routine
The workflow below is deliberately a sequence rather than a promise of automatic processing. Each box is short, bounded and read in order: verify the route; sign in without sharing secrets; check the requested action and acknowledgement; then retain the record and escalate only through official support if something does not match.
What NPS Central does not change
- Your investment outcome remains market-linked where your scheme has market exposure. A portal cannot guarantee returns.
- The applicable NPS rules, account eligibility, KYC requirements, charges and service processes continue to matter. Check the current official terms for your account and request.
- A new digital channel does not make an unverified payment instruction safe. Match every contribution or service request to your own records.
When Abhipra can help
Abhipra has acted as a Point of Presence for 17 years. For NPS account-opening or service guidance, start with Abhipra NPS & Pension services. If you are ready to explore an NPS account, use Abhipra’s approved NPS account-opening route. A sustainable contribution routine can be explored through Abhipra’s approved NPS SIP route.
Source links / disclaimer
- PFRDA NPS Diwas 2026 programme and current NPS materials
- PFRDA active circulars
- Contemporary NPS Central launch coverage
This article is investor education, not investment, tax, legal or cybersecurity advice. Digital NPS services and operating processes may change; verify the current official instructions before acting.