No Nomination or Documentation: The Investor Mistake That Can Delay a Claim
Investment planning is incomplete when family members cannot identify holdings or locate the records needed to begin a transmission request. Nomination and documentation do not replace succession law or personal legal advice, but they can make the service process clearer.
What nomination does—and does not—do
SEBI’s May 2026 circular says a single demat account or mutual-fund folio opened after implementation requires a nomination unless an opt-out declaration is submitted; joint holdings have different rules. It also says investors can provide up to three nominees. Read SEBI’s May 2026 nomination circular.
AMFI explains that nomination lets an eligible individual unitholder nominate a person who can claim units or redemption proceeds on death, subject to the required process. It notes that a nominee may have to complete KYC and provide proof of death and other documents; nomination is therefore not a substitute for checking estate and succession implications. Read AMFI’s nomination guidance.
A records-first routine
- List each demat account, mutual-fund folio, broker and bank link.
- Confirm the current nomination or opt-out choice directly with the relevant regulated provider.
- Check nominee names, allocation and contact details after major family changes.
- Keep account statements, contract notes, folio details, nomination acknowledgement and contact routes together.
- Tell a trusted family member where the records are held without sharing passwords, OTPs or PINs.
What the workflow shows
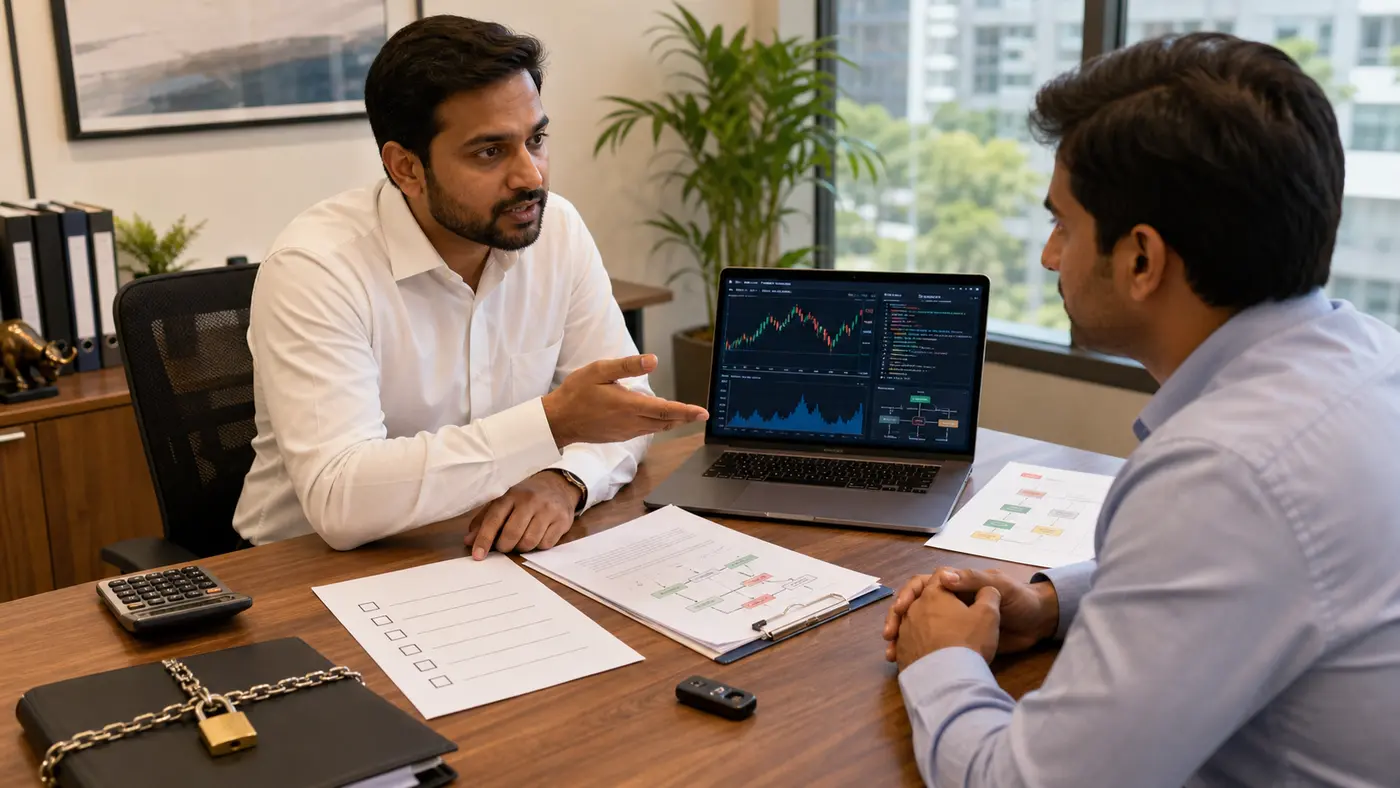
The workflow is deliberately simple: identify holdings, confirm nomination choice, preserve documents, then update the record after a material change. The inference is that a current record reduces uncertainty; it does not guarantee transmission or override applicable law.
| Keep | Why |
|---|---|
| Statements and folio/account identifiers | They help identify the holding and provider. |
| Nomination acknowledgement or opt-out record | It helps verify the choice recorded with the provider. |
| Provider contact and grievance route | It supports a prompt, documented service request. |
Investor checklist
- Use only the official provider portal or service centre to update nomination.
- Do not share account credentials or OTPs with family members, callers or agents.
- Review both demat and mutual-fund holdings; their records may be separate.
- Obtain legal advice for wills, succession, joint holdings or disputed claims.
- Preserve the service acknowledgement after every change.
Source Links
- SEBI: modified nomination norms, May 2026
- AMFI: nomination facility and process
- SEBI Investor: nomination overview
Disclaimer
This is investor education, not legal, tax or succession advice. Nomination and transmission outcomes depend on the applicable law, provider rules, records and facts. Investments in securities are subject to market risks. Reviewed by Abhipra Research / Compliance Team.