NPS Vatsalya for NRI and OCI Families: Eligibility and Account Checklist
If your family lives overseas, NPS Vatsalya may still be relevant for an eligible child—but the account-opening details need extra care. PFRDA’s current guide includes eligible NRI and OCI cases for children below 18. The minor is the subscriber and beneficiary; a parent or legal guardian operates the account while the child is under 18.
Start with the child’s eligibility
PFRDA’s scheme guidance says an eligible child must be below 18. It includes eligible NRI and OCI cases. Residence abroad by itself does not establish eligibility, so ask a registered Point of Presence (PoP) or CRA to confirm the child’s exact status before applying.
The account is opened in the minor’s name and the minor is its sole beneficiary. The parent or legal guardian manages it for the child. A guardian living overseas does not make the account the guardian’s investment account.
What overseas families should prepare
The NRI/OCI application path has a key banking requirement: prepare the minor’s sole or joint NRE/NRO bank-account details. The NRI/OCI registration instructions also say contributions should be made through NRE/NRO accounts and that transfers must comply with applicable RBI and FEMA requirements.
Keep these items ready for the registered PoP/CRA to check:
- The child’s date-of-birth proof, such as a birth certificate, school-leaving or matriculation certificate, PAN, or passport, as applicable.
- The guardian’s current KYC documents and PAN or Form 60, as applicable. A court-appointed guardian should also confirm what appointment evidence is required.
- The child’s sole or joint NRE/NRO bank-account details for the NRI/OCI route.
- The appropriate NRI/OCI application and any country-of-tax-residence information requested by the provider.
The accepted form, authentication method, and document formats can depend on the PoP or CRA’s current process. Check its latest checklist before sending documents. Never email unmasked identity or bank documents to an unverified contact.
Follow the application path
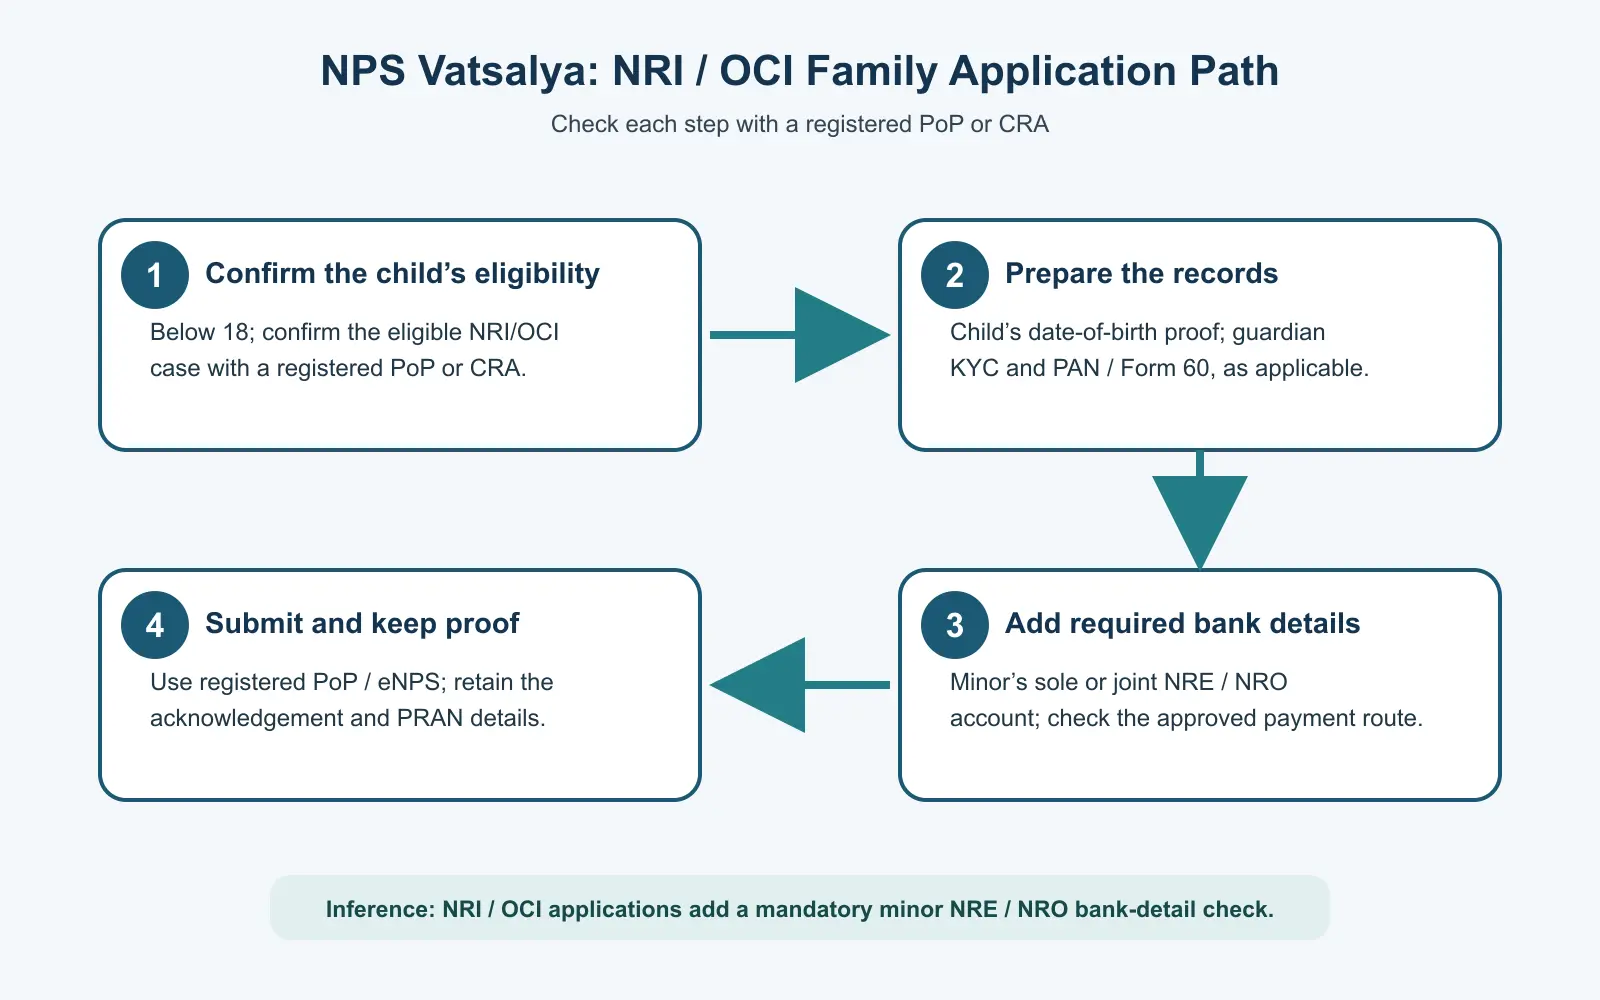
The workflow image below has no numeric axes: it is a sequence of eligibility and document checks, not a quantitative comparison. Its inference is operational—the overseas account path adds a mandatory NRE/NRO bank-detail step before application submission. The labels are repeated here in selectable text: confirm eligibility, prepare child and guardian records, include the required NRE/NRO details, then submit through a registered PoP or eNPS and retain the acknowledgement and PRAN details.
Contributions and investment risk
The current PFRDA guide lists a minimum of ₹250 at opening and ₹250 in each financial year, with no maximum contribution limit. Contributions are invested by a Pension Fund and returns are market-linked; they are not guaranteed. For an NRI/OCI case, confirm the currently accepted payment method and any transfer requirements with the provider before remitting money.
NPS Vatsalya is a long-term, market-linked account for a minor. It is not a substitute for near-term education funding or an emergency reserve. Consider the family’s goals, liquidity needs, investment risk and cross-border tax position before contributing.
Questions families often ask
Can an overseas parent open the account for a child?
PFRDA guidance includes eligible NRI/OCI cases for children under 18. Confirm the child’s specific eligibility with a registered PoP or CRA; the guardian’s overseas residence alone is not enough to decide.
Is a bank account needed at application?
For the NRI/OCI route, the minor’s sole or joint NRE/NRO bank-account details are required under the scheme guidelines. The official application instructions also direct NRI/OCI contributions through NRE/NRO accounts, subject to applicable RBI and FEMA requirements.
Who owns the account?
The minor is the subscriber and sole beneficiary. The parent or legal guardian operates the account for the child while the child is under 18, subject to the scheme rules.
A careful start for overseas families
Confirm eligibility first, then assemble the minor’s date-of-birth proof, guardian KYC and PAN/Form 60, and the minor’s NRE/NRO account details. Ask the PoP or CRA to verify the latest NRI/OCI checklist and contribution route before submitting.
For an overview of Abhipra’s NPS and pension services, see the service page. Abhipra has acted as a Point of Presence for 17 years.
This article is for investor education only and is not investment, tax, legal or immigration advice. NPS is market-linked and returns are not guaranteed. Cross-border eligibility, transfer, FEMA and tax questions should be checked with the relevant official authority and registered NPS intermediary before acting.