NPS Investment Choice Review: How Often Can You Change It?
Changing an NPS choice can be useful when your retirement horizon, risk comfort or account circumstances change. It is not a reason to chase the latest one-year return. Start with the rule that applies to your NPS sector, then check the choice already recorded against your retirement plan.
The frequency depends on the account route
For the All Citizen and Corporate NPS models, the current PFRDA FAQs say that a subscriber can change the Pension Fund once in a financial year and the investment choice four times in a financial year. The usual request routes are an authenticated subscriber login or a physical application through a Point of Presence (PoP).
These limits are not universal. Central Government subscribers have a different investment-pattern frequency. UPS subscribers also have separate rules. A Corporate subscriber whose employer made the original Pension Fund or allocation choice may have an employee revision option after 365 days. Check the sector shown in your account record before taking action.
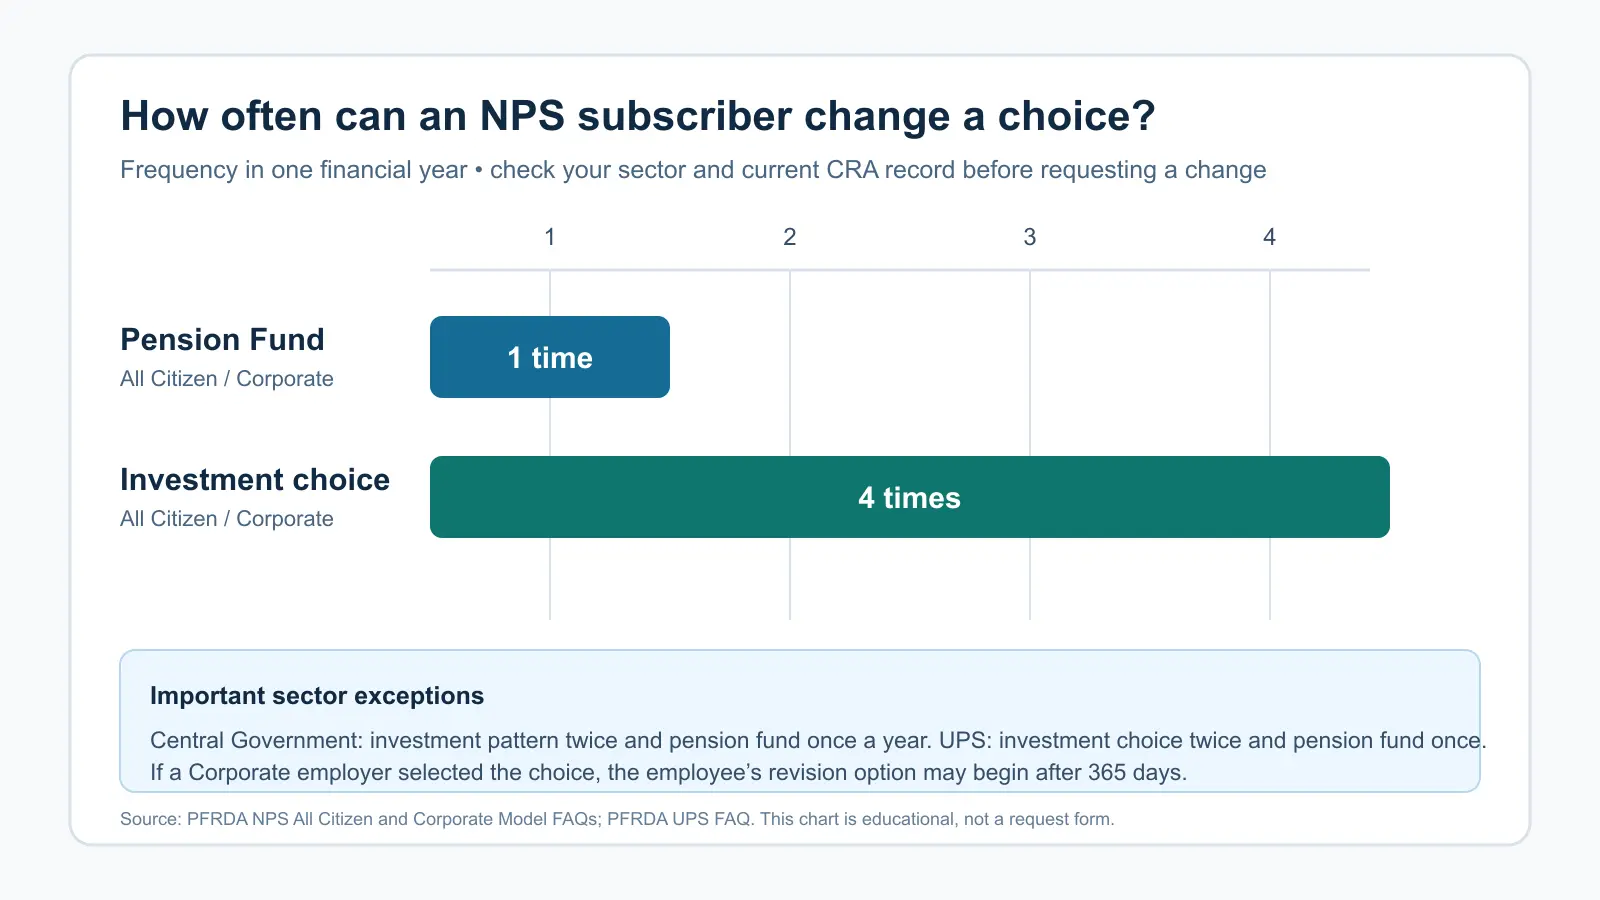
The chart’s horizontal axis is the number of permitted changes in one financial year. Its two bars compare the All Citizen and Corporate limits only: one for Pension Fund and four for investment choice. The practical inference is that investment-choice flexibility does not make frequent changes a good idea; the decision should still fit the long-term retirement objective.
What exactly are you changing?
Under the common NPS schemes, the Pension Fund is the regulated fund manager. Investment choice is the way contributions are allocated. In Active Choice, the subscriber selects an allocation within the prescribed limits. In Auto Choice, allocation follows a life-cycle approach that changes with age. Market-linked returns can move up or down; neither a Pension Fund change nor an allocation change assures a result.
For non-government subscribers using the Multiple Scheme Framework (MSF), the product structure has an additional constraint: PFRDA says the chosen MSF scheme has a 15-year minimum lock-in. During that period, a subscriber may move to common NPS schemes but cannot switch between MSF schemes. Do not apply the common-scheme frequency chart to an MSF switch without checking the scheme record and current rule.
A four-step review before you submit a request
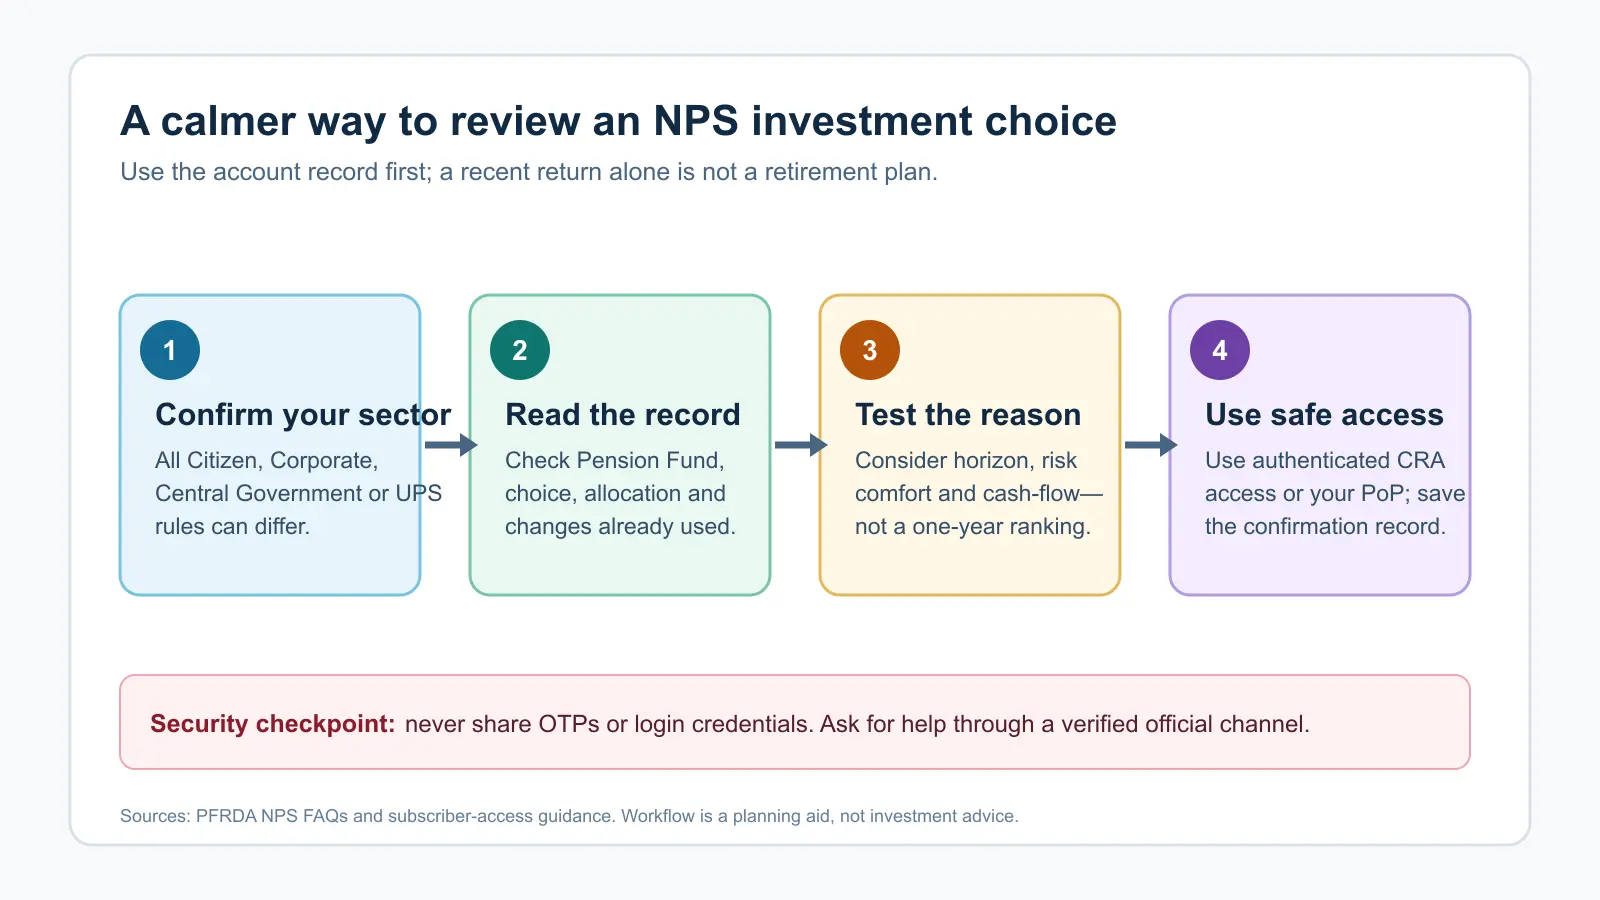
- Confirm the sector and scheme. Distinguish All Citizen, Corporate, Central Government, UPS and MSF arrangements. The route affects both available options and change frequency.
- Read the account record. Note your current Pension Fund, investment choice, allocation, existing changes in the financial year and any employer-selected setting.
- Test the reason for a change. Consider years to retirement, ability to tolerate market movement, income stability and the role of NPS alongside EPF, PPF or other investments. A short performance table is not enough on its own.
- Use verified access and retain evidence. Make the request through authenticated CRA access or through your PoP, then keep the acknowledgement and review the next account statement. Never share OTPs, passwords or login credentials with someone offering to make a change for you.
The workflow is a control sequence, not an investment recommendation. Its key inference is simple: record accuracy and suitability come before the request.
When restraint can be the better decision
An allocation review can be sensible after a material change in income, retirement timing or risk capacity. It may be less useful after a brief market move or a headline about a recent top performer. NPS is designed for retirement; frequent reaction can disconnect the portfolio from the original horizon. If the account details are unclear, first obtain the current record and resolve the discrepancy rather than repeatedly submitting changes.
Need help with the record or route?
Abhipra has acted as a Point of Presence for 17 years. For help understanding the NPS service route or servicing requirements, visit Abhipra NPS & Pension services. If you are eligible and wish to start an account, use Abhipra’s NPS account-opening route. This article is educational; consider your full financial position and seek suitable professional advice before changing a long-term allocation.
Source links and disclaimer
- PFRDA: NPS All Citizen Model — common-scheme choices, MSF features and frequency information.
- PFRDA: All Citizen Model FAQ — choice-change frequencies and request modes.
- PFRDA: Corporate Model FAQ — Corporate-sector frequency and employer-choice qualification.
- PFRDA: UPS investment FAQ — UPS choice-change frequency.
NPS investments are market-linked. Rules, operational routes and available schemes can change; verify the current position through official NPS channels before acting.