NPS Multiple Scheme Framework: More Choice Needs a Better Review Routine
Non-government NPS subscribers can now access multiple schemes under the Multiple Scheme Framework (MSF). That flexibility can help align a retirement account with risk comfort and retirement needs, but it does not make higher returns certain or remove the need to read scheme disclosures.
What MSF changes
From 1 October 2025, non-government NPS subscribers can invest in multiple schemes using a single or multiple PRAN linked to their PAN. PFRDA says investments can be viewed through a consolidated statement. MSF schemes are offered by Pension Funds and approved by PFRDA for non-government subscribers.
The important distinction is between choice and outcome. A scheme’s risk label, investment design, costs, lock-in and disclosures matter more than a recent return. NPS remains market linked.
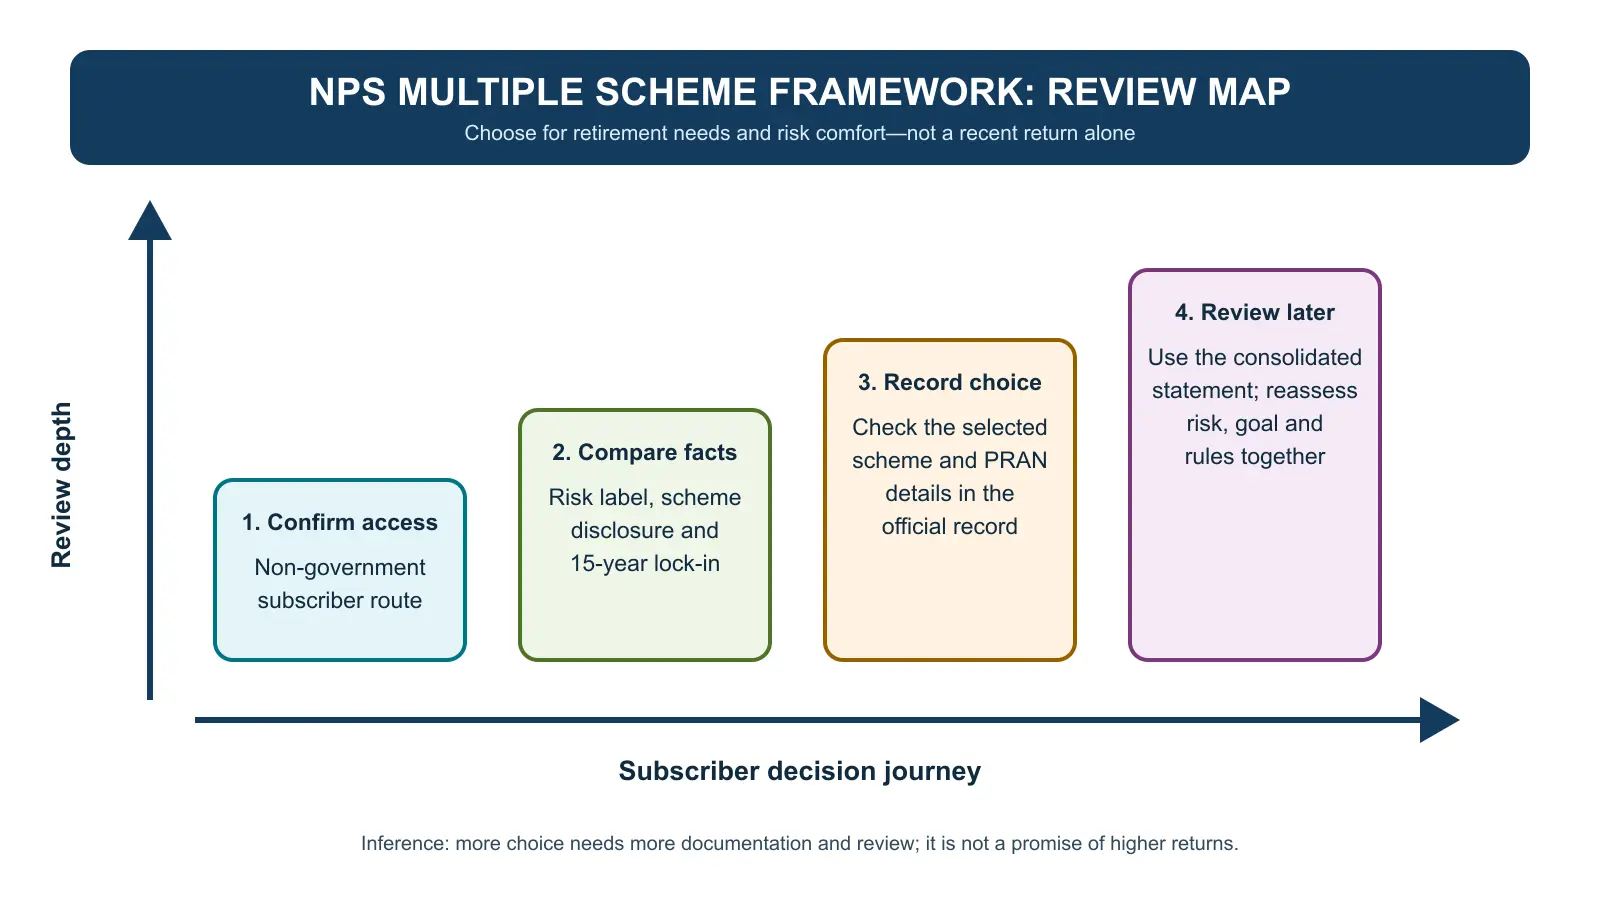
The map is a decision workflow, not a performance forecast. Its horizontal axis shows the order of a careful review; its vertical axis shows how much verification is needed. The inference is that additional choice needs stronger record-keeping and periodic review. PFRDA’s current All Citizen information says an MSF scheme has a 15-year lock-in; during that period a subscriber may move to Common Schemes but cannot switch between MSF schemes. After 15 years, switching between MSF schemes or exit may be available under the applicable rules.
Four checks before choosing a scheme
| Check | Practical question |
|---|---|
| Eligibility | Is this a non-government NPS route and is the selected scheme available for your account? |
| Risk and objective | Does the risk category and investment approach match your time horizon and capacity for volatility? |
| Lock-in and exits | Have you understood the 15-year scheme lock-in and the applicable movement or exit rules? |
| Account record | Can you identify the selected scheme and contribution record in the official consolidated statement? |
Keep the comparison factual
- Compare the official risk label, disclosures, benchmark and applicable charges—not a one-year return in isolation.
- Keep a note of why the scheme fits the retirement goal and when it will be reviewed.
- Confirm every change in the official account record. Do not share login credentials or OTPs with anyone.
- Exit and withdrawal rules apply uniformly to Common Schemes and MSF schemes, except where a specific-purpose scheme has separate guidelines.
Where Abhipra can help
Abhipra has acted as a Point of Presence for 17 years. Explore Abhipra’s NPS & Pension services for service information or use the approved Abhipra NPS account-opening route for a new account. Verify the current scheme and service route before taking action.
Source links and disclaimer
- PFRDA: NPS All Citizen Model and MSF information
- PFRDA: Introduction of MSF circular, 16 September 2025
- PFRDA: All Citizen exit and withdrawal FAQs, March 2026
This is educational information, not investment, tax or legal advice. NPS is market linked. Verify current scheme terms, eligibility and regulatory requirements before acting.