NPS Vatsalya Contributions: A Parent’s Minimums, Frequency and Record-Check Guide
NPS Vatsalya lets a parent or legal guardian build a long-term, market-linked pension corpus for a minor. The practical question is not only how much to contribute, but also how to keep the payment trail and account record in order. This guide uses the current PFRDA contribution framework and avoids return projections.
Start with the three contribution thresholds
The current minimum is ₹250 at account opening, ₹10 for a subsequent contribution and ₹250 in each financial year. There is no maximum contribution limit and no limit on how many contributions may be made in a financial year. These are contribution rules, not a suggested amount or an expected investment outcome.
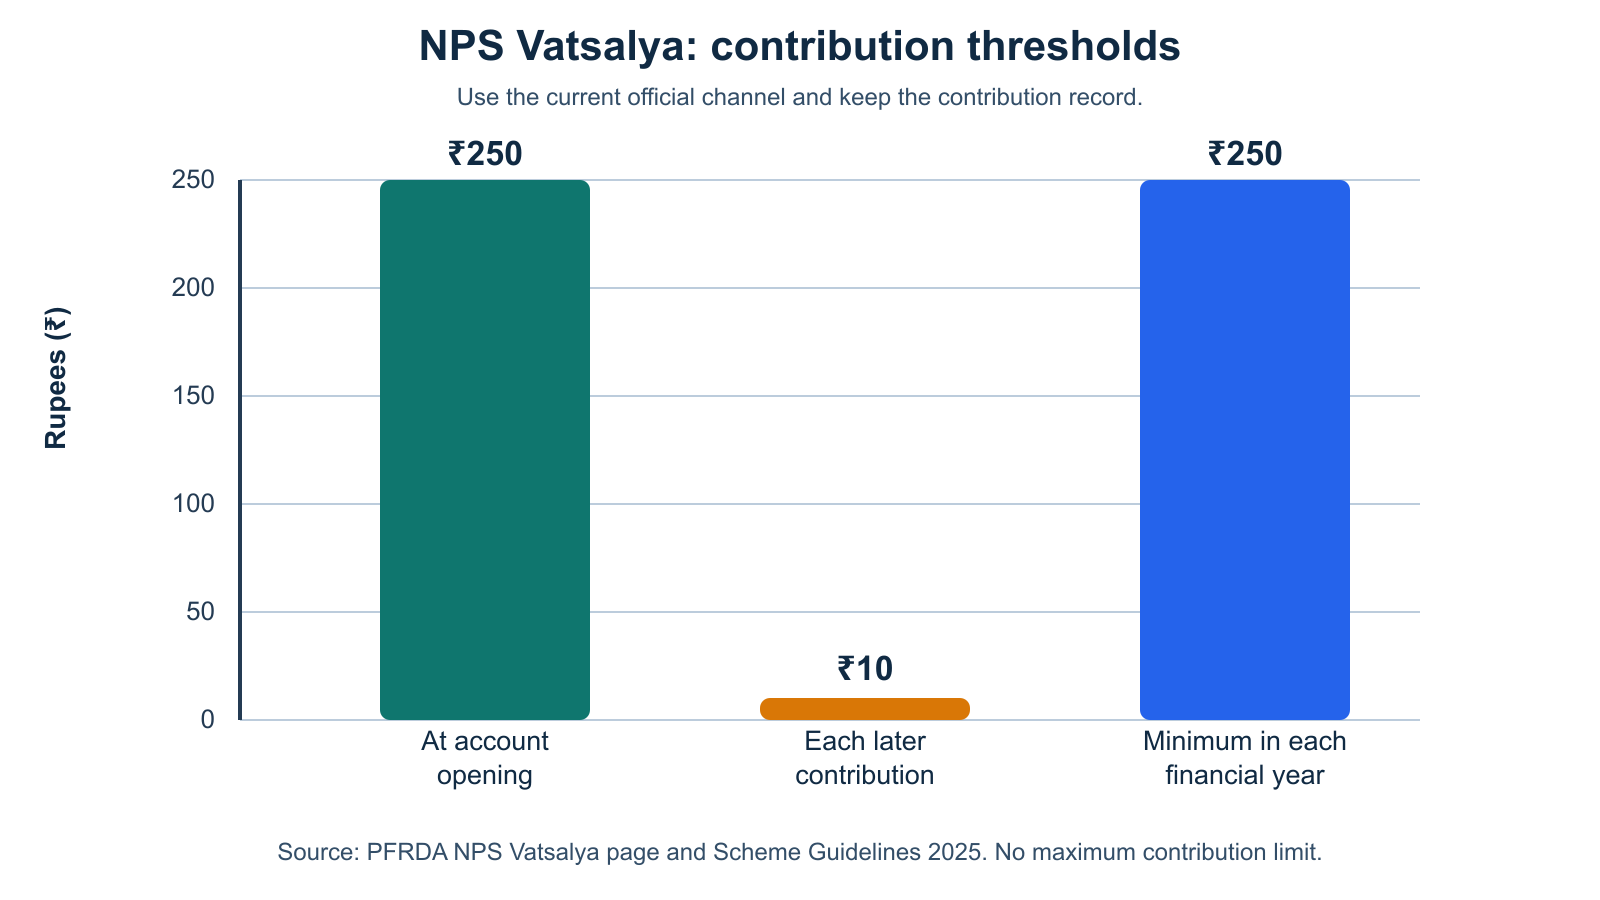
The vertical axis is rupees and the horizontal axis identifies the requirement. The opening and financial-year bars are each ₹250, while the individual later-contribution bar is ₹10. The inference is simple: an annual minimum does not require a single payment; a guardian can choose timing and amounts within the current rules. Contributions remain market-linked after investment, so the chart does not show returns, growth or a recommended saving amount.
Choose the route carefully, then retain proof
Parents and legal guardians may contribute through registered Points of Presence, online facilities offered by PoPs, eNPS, UPI apps and other electronic modes approved by PFRDA from time to time. Use only a verified channel. Before paying, confirm the minor’s account details and the guardian information shown in the current account record. After paying, retain the receipt or transaction reference and then confirm that the contribution appears in the official CRA record.
A small control routine can prevent bigger follow-ups
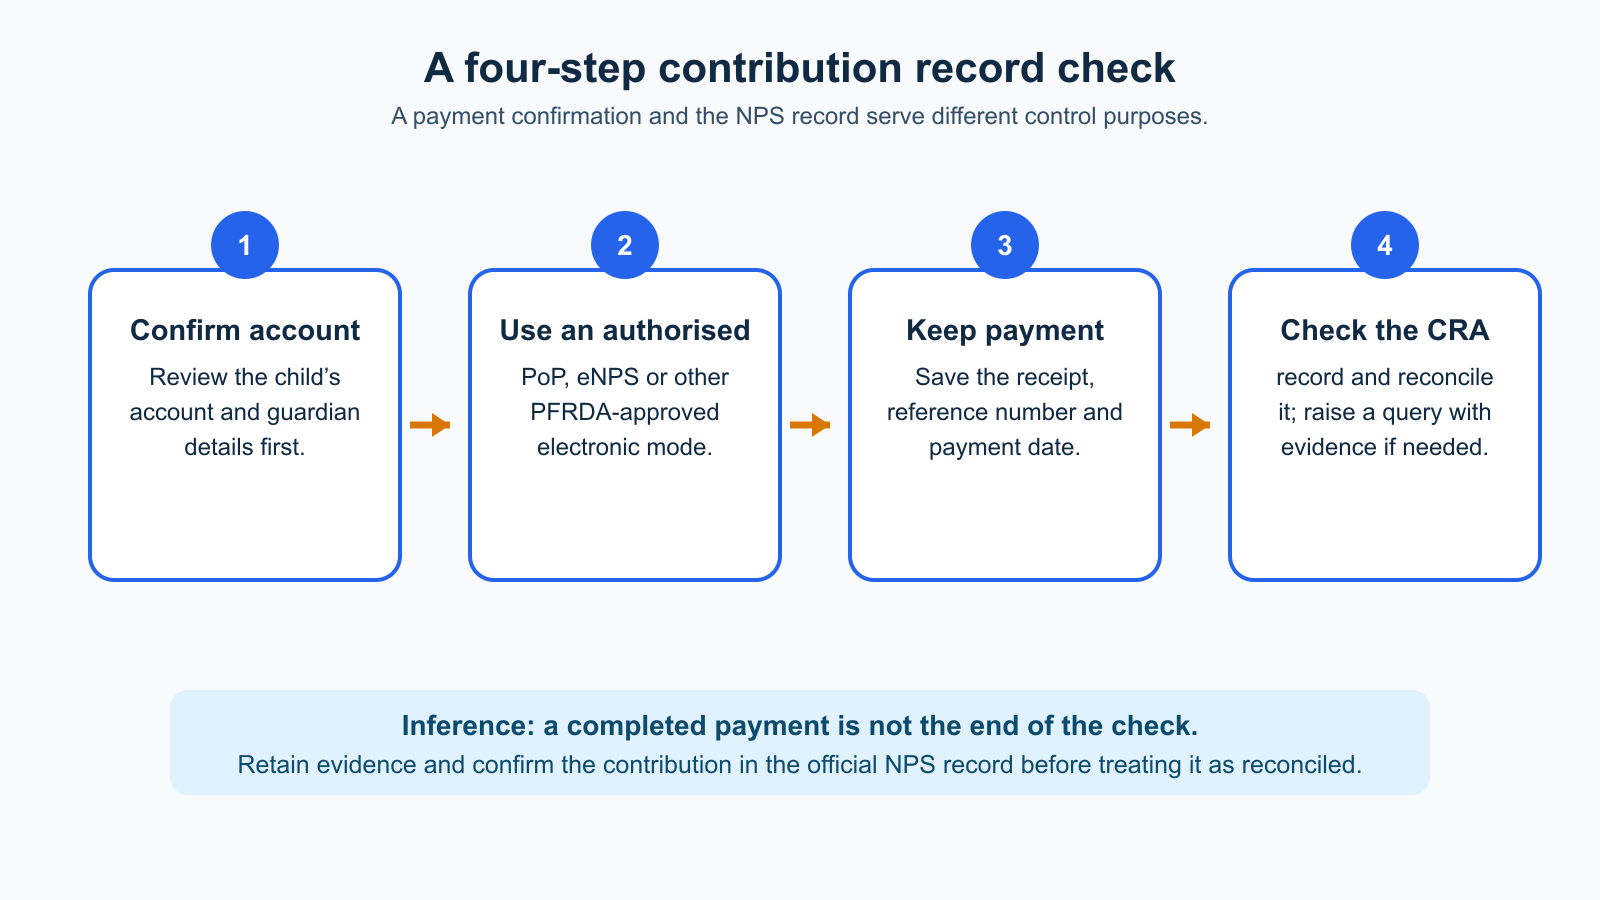
The workflow has no axes because it shows a sequence rather than measured data. Its inference is that a successful payment message is useful evidence, but it is not the final reconciliation step. Keep the transaction reference, compare it with the account record, and use the applicable authorised channel for support if the entry is missing or incorrect.
- Confirm the account. Check the minor subscriber’s details and the guardian’s contact details before initiating a contribution.
- Use an authorised route. Use a registered PoP, its verified online facility, eNPS or another PFRDA-approved electronic mode. Do not follow payment links received in unexpected messages.
- Retain evidence. Save the payment date, amount, transaction reference and acknowledgement. Avoid sharing account credentials or OTPs with anyone.
- Reconcile the record. Review the CRA transaction or statement record. A market-linked investment can have a changing value; first confirm the contribution and units/transaction details rather than judging the account by a short-term value movement.
Keep the contribution amount suitable for the family plan
NPS Vatsalya is designed for long-term financial security of a minor; it should not replace money needed for near-term education fees, medical needs or an emergency reserve. Parents and guardians can decide whether a one-time, occasional or planned contribution pattern fits their cash flow, provided the applicable annual minimum is met. Relatives and friends can also contribute, but the family should retain a clear record of who paid and ensure that the account details used are correct.
At 18, fresh KYC is mandatory. The subscriber may continue in NPS Vatsalya up to age 21, shift the corpus to NPS, or exit, subject to the applicable rules. Keeping clean contribution evidence and updated contact details can make that later transition easier to review.
How Abhipra can help
Abhipra has acted as a Point of Presence for 17 years. Review Abhipra NPS & Pension services for current service information and use Abhipra’s approved NPS account-opening route when an eligible family is ready to start. Account opening and servicing remain subject to current KYC, scheme and operational requirements.
Frequently asked questions
Is ₹10 the annual minimum for NPS Vatsalya?
No. ₹10 is the current minimum for a subsequent individual contribution. The current minimum contribution in each financial year is ₹250; opening the account also requires at least ₹250.
Is there a maximum number of contributions in a financial year?
No. PFRDA’s current NPS Vatsalya page says there is no restriction on the number of contributions in a financial year, and there is no maximum contribution limit.
Does a contribution earn a guaranteed return?
No. NPS Vatsalya is market-linked. The invested value can rise or fall with the selected Pension Fund and investment approach; no return is guaranteed.
Can a contribution be treated as complete as soon as the payment message arrives?
Keep the payment acknowledgement, but also check the official CRA record. The payment evidence and the NPS account record are both useful when reconciling a contribution.
This article is for investor education, not investment, tax or legal advice. Rules, available channels, charges and tax treatment can change. Review current official disclosures and your own financial circumstances before contributing.