Tax Saving vs Retirement Planning: Don’t Let March Decide Your NPS Strategy
Most tax decisions are made near a deadline. Retirement decisions have to work for decades. NPS can connect the two, but a deduction should be the result of a suitable retirement plan—not the reason for buying one.
Start with the job your money must do
Tax saving answers a one-year question: “What deduction can I claim for this financial year?” Retirement planning answers a longer one: “How will I create income when my salary or business income slows down?”
NPS Tier I is designed for retirement. It is market-linked, has an exit framework and may require part of the corpus to be used for an annuity at exit. That can make it useful for disciplined long-term saving, but it also means it should not be funded with money needed for an emergency, short-term education expense or a near-term property payment.
The tax facts in one view
| Tax provision / choice | Current practical point | Planning inference |
|---|---|---|
| 80C, 80CCC and 80CCD(1) | The combined old-regime ceiling shown by the Income Tax Department is Rs. 1.5 lakh. | Check what has already used this shared space before treating NPS as an extra deduction. |
| 80CCD(1B) | An additional deduction of up to Rs. 50,000 is shown for eligible contribution, separate from the amount claimed under 80CCD(1). | Useful only if the retirement commitment suits you and the applicable tax regime permits the claim. |
| New tax regime | The ITR guidance enables employer Tier-I NPS contribution under 80CCD(2), but not personal 80CCD(1) or 80CCD(1B) deductions when the taxpayer has not opted for the old regime. | Do not assume a personal NPS contribution reduces tax under the new regime; confirm your regime and payroll facts. |
The table is a tax-rule snapshot, not a return forecast. Its rows compare the deduction route; its practical inference is that eligibility must be checked before contribution, not after it.
A three-check decision workflow
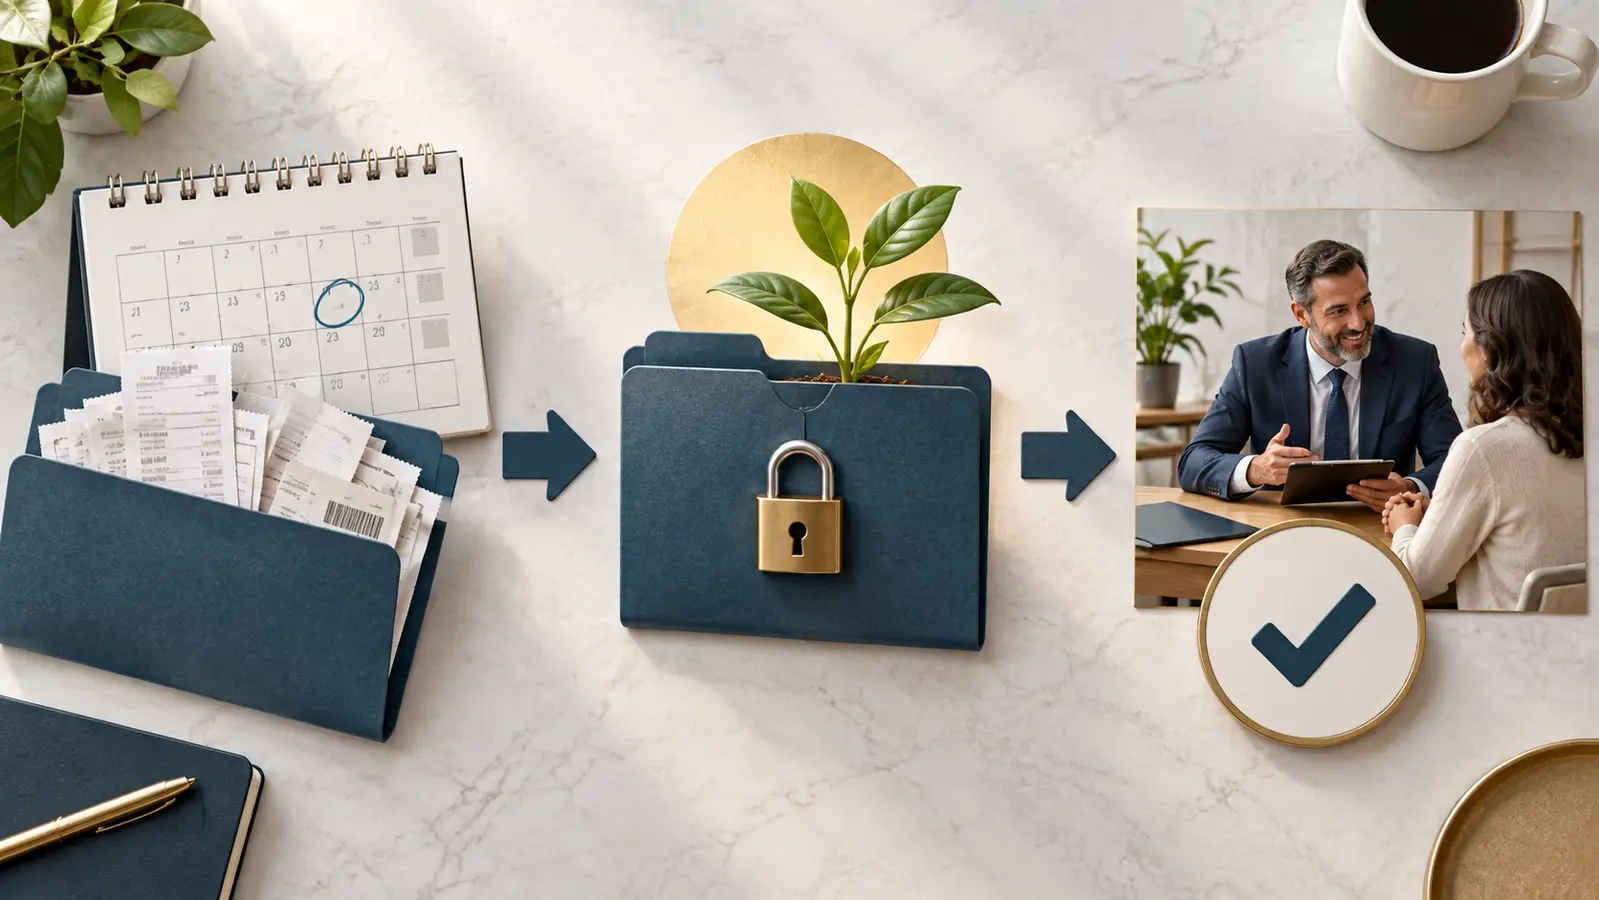
First, confirm your tax regime and whether you have unused eligible deduction capacity. Second, test the contribution against your emergency fund, insurance, debt repayments and nearer goals. Third, choose NPS only if the long-term retirement role, market risk and access restrictions are acceptable—not simply because a deadline is approaching.
This workflow is deliberately not a return chart: it has no numeric axis because it ranks decision checks rather than forecasting investment performance. Its left-to-right direction shows the appropriate sequence—tax eligibility, retirement fit, then implementation. The inference is simple: a tax benefit can strengthen a good retirement decision, but cannot repair a poor cash-flow decision.
Questions to ask before contributing
- Have I kept a separate emergency reserve and funded goals due in the next few years?
- Am I comfortable with market-linked value changes and the NPS exit structure?
- Which tax regime will apply to me for the relevant year, and which contribution route is actually eligible?
- If I am salaried, is the contribution personal or employer-funded, and has payroll documented it correctly?
- Have I kept my PRAN and contribution record ready? The Income Tax Department requires PRAN details for 80CCD(1) and 80CCD(1B) claims.
Where NPS can fit
For an investor with a long horizon, stable cash flow and a clear retirement-income gap, NPS may be one part of a wider plan. It can complement EPF, PPF, mutual funds and insurance; those products serve different roles and should not be forced into a single tax-saving comparison.
Abhipra has acted as a Point of Presence for 17 years. You can learn about NPS & Pension services, use the online NPS account-opening journey, or explore the NPS SIP contribution facility. A tax professional can confirm individual eligibility and an authorised payroll/compliance team should confirm employer-contribution treatment.
Source links and disclaimer
- Income Tax Department: deductions and tax regimes for AY 2026-27
- Income Tax Department: ITR guidance for NPS deduction fields
- PFRDA: NPS All Citizen Model information
This article is for investor education, based on sources checked on 14 September 2026. Tax law, forms, limits and NPS rules can change. It is not tax, legal or investment advice, and it does not promise returns. Consider your goals, risk appetite, liquidity needs and applicable rules before investing.