New NPS Scheme Labels: How to Compare Options Without Chasing a Name
NPS choices may look different after PFRDA’s 28 August 2026 scheme-classification framework. The purpose is comparability—not a signal that one category will deliver better returns.
Start with the type of choice
The framework presents a subscriber journey in this order: choose a scheme type, then the relevant category or allocation, then the Pension Fund. Lifecycle schemes adjust E, C and G allocation with age. Active Choice lets the subscriber allocate across the available asset classes within regulatory limits. NPS Sanchay has a predefined pattern for the informal sector. MSF schemes are grouped by their equity-allocation mandate.
A clearer risk range for MSF schemes
| MSF category | Equity mandate | Reader inference |
|---|---|---|
| A: Aggressive Growth | 80%–100% | Highest equity exposure in this classification; value may fluctuate substantially. |
| B: High Growth | 60%–80% | Still equity-led; compare the disclosed risk and long-term fit. |
| C, D and E | 35%–60%, 10%–35%, and 0%–10% | Lower equity bands do not remove investment risk; read the scheme details. |
The categories form a risk-exposure scale, not a performance chart. The axis is the scheme’s permitted equity range, from lower to higher. The inference is that a category describes the mandate; it does not predict return.
Follow the comparison sequence
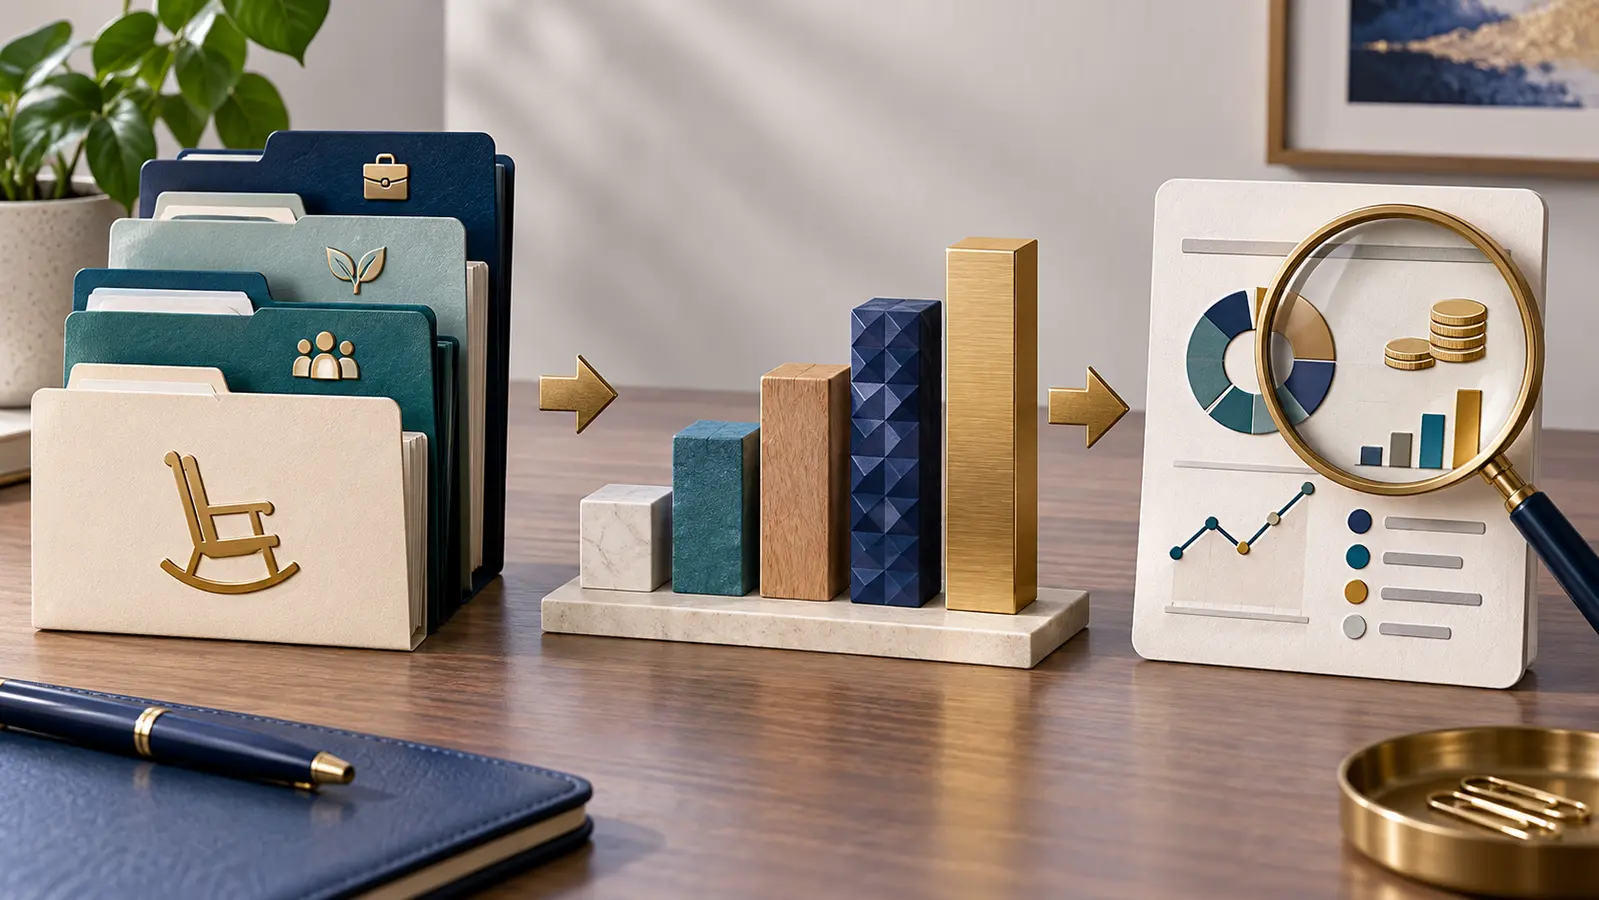
Use the visual as a sequence: first choose the investment approach that fits your retirement horizon; next identify the category or allocation you can stay with through market movement; then compare Pension Fund disclosures. Subscriber-facing interfaces are required to show, among other information, the scheme and fund name, launch date, historical and benchmark returns, charges, riskometer and previous-month AUM before selection.
The workflow has no numeric axis because it describes an order of decisions. Its left-to-right direction is the inference: do not begin with last year’s return. Begin with purpose and risk capacity, then compare like with like.
Important limits and changes
- Under Active Choice, the published Tier I maximum for equity and related instruments is 75%; corporate bonds and government securities may each be allocated up to 100%, subject to the overall allocation rules.
- A subscriber can hold one Lifecycle or Active Choice scheme at a time under the same PRAN, while more than one MSF scheme may be held.
- The circular permits a maximum of two change requests per account in a financial year for a Pension Fund, investment scheme, or their combination.
- Existing MSF labels may be renamed, reclassified, merged or restructured under the operational circular. Read the communication from your Pension Fund or CRA; a label change alone is not a reason to transact.
Where Abhipra can help
Abhipra has acted as a Point of Presence for 17 years. Read about NPS & Pension services, use the online NPS account-opening journey, or explore the NPS SIP contribution facility. Suitability depends on goals, time horizon, liquidity needs and risk capacity.
Source links and disclaimer
- PFRDA circular: standardised scheme framework, 28 August 2026
- PFRDA circular: operationalising the framework, 28 August 2026
This investor-education article was checked on 15 September 2026. NPS rules, schemes, fees and disclosures may change. It is not investment, tax or legal advice and does not promise returns.