NPS Sanchay Normal Exit: The 15-Year Check Before You Start
For an informal-sector worker, a flexible contribution route can be useful. But flexibility in paying does not make a pension account an emergency fund. Before enrolling in NPS Sanchay, understand when normal exit becomes available and how the accumulated pension wealth is structured at that point.
The timing rule to put on your calendar
Normal exit becomes available after 15 years of subscription or at age 60, whichever is earlier. A subscriber may also continue in the scheme up to age 85. Those timing rules make the account most appropriate for money set aside for retirement, after essential short-term needs and an emergency buffer have been considered.
How the normal-exit allocation works
At normal exit, up to 80% of the accumulated pension wealth may be withdrawn as a lump sum; at least 20% is used to purchase an annuity. If the accumulated corpus is up to Rs 8 lakh, the subscriber may use the full lump-sum option instead.
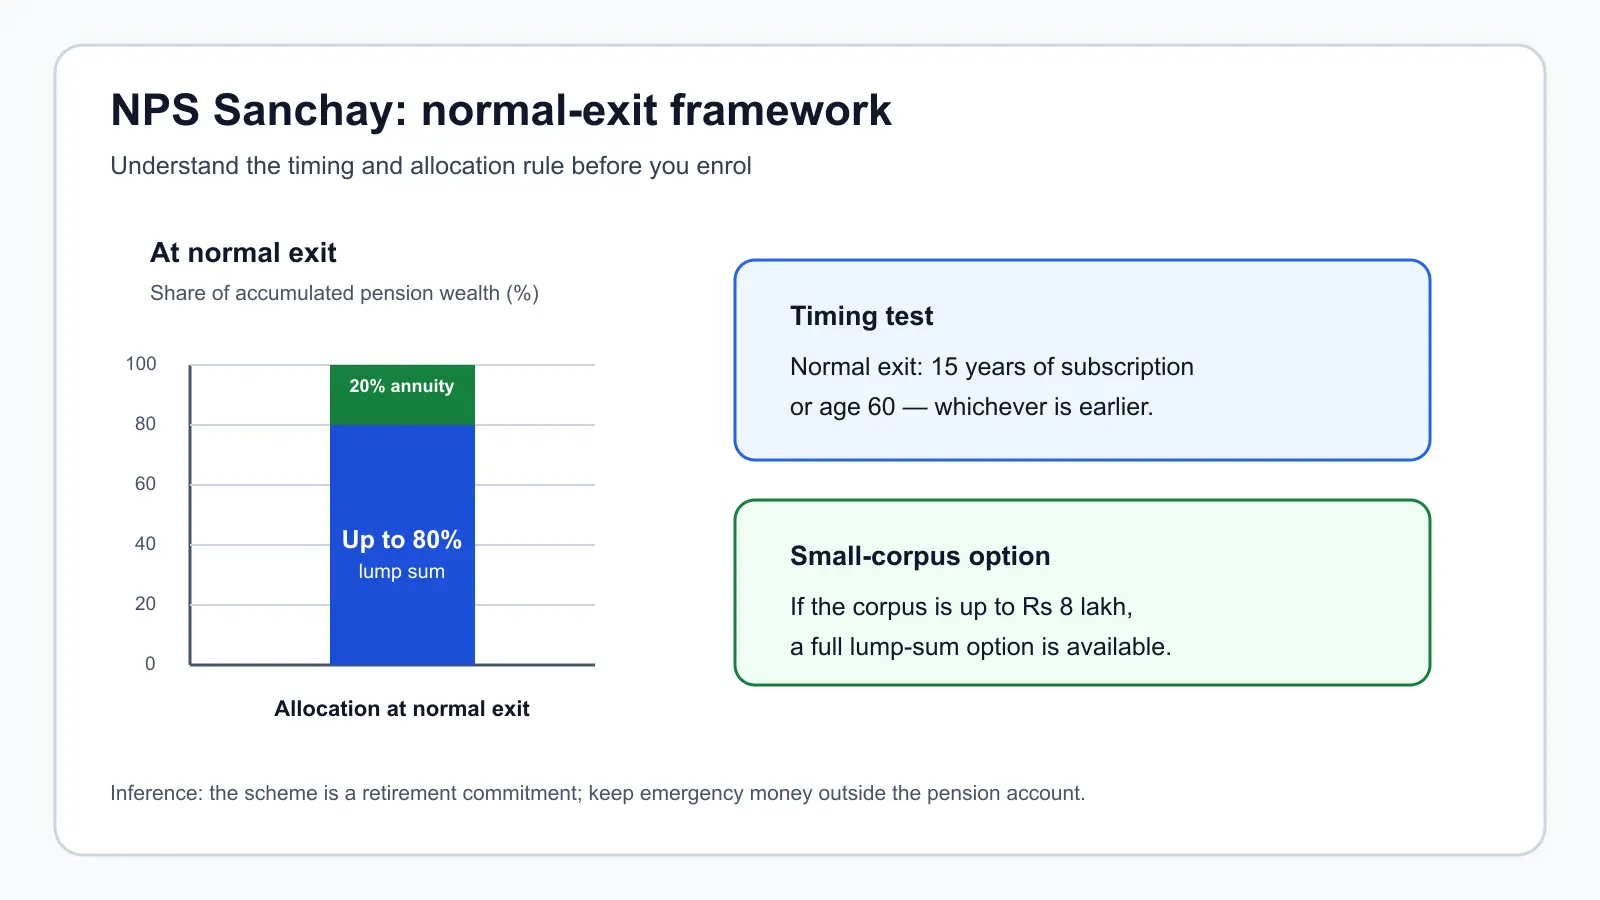
The vertical axis shows the percentage of accumulated pension wealth. The blue segment represents a lump sum of up to 80%; the green segment represents an annuity share of at least 20%. The timing panel is an either-or test: 15 years of subscription or age 60, whichever comes first. The practical inference is simple: protect emergency money separately so that a retirement account does not need to solve a short-term cash-flow problem.
A short pre-enrolment check
- Decide whether your income can support contributions without compromising rent, food, insurance or emergency savings.
- Keep KYC and PRAN records current, and retain contribution confirmations.
- Read the applicable exit and withdrawal rules before committing a large contribution.
- Remember that NPS Sanchay is market-linked; contributions and account access do not create a guaranteed return.
Abhipra has acted as a Point of Presence for 17 years. Explore NPS & Pension services at Abhipra, the approved NPS account-opening route, or the NPS SIP route.
Source links and disclaimer
- PFRDA: NPS Sanchay — eligibility, contribution and exit framework.
- PFRDA: Introduction of NPS Sanchay — scheme introduction and regulatory context.
This is investor education, not individual investment, tax or legal advice. Rules can change; review the current official material before acting.