Term Insurance: How Income Earners Can Review Household Protection
For a household that depends on an income, the financial question is not whether a policy has a maturity value. It is whether essential obligations could continue if that income stopped because of the death of the insured person during the policy term. Term insurance is one way to address that question, subject to the policy terms, underwriting and the household's actual needs.
What term insurance is designed to do
IRDAI's Introduction to Insurance describes life insurance as a financial cover for contingencies linked to human life. Its term-insurance description is specific: the sum assured is paid only on the death of the insured during the period specified, and there is no maturity value.
That design makes the review question practical: would the stated benefit, if a covered claim arose, help the household meet essential living costs, debt obligations and planned responsibilities? The answer can differ for each earning member and household. A non-earning family member's caregiving contribution can also be financially significant, so the discussion should not be reduced to a one-size-fits-all rule.
Turn household responsibilities into review inputs
| Household area | Question to record | Documents or facts to review |
|---|---|---|
| Income continuity | Whose income or household contribution would need to be replaced? | Dependants, essential spending, current savings and existing employer benefits. |
| Debt and commitments | Which loans or time-bound commitments could remain? | Loan schedules, co-borrower obligations, education plans and care responsibilities. |
| Policy fit and administration | Are the policy term, premium commitment, nominee and claims contacts understood? | Policy schedule, exclusions, premium dates, nominee acknowledgement and claim instructions. |
A current IRDAI rule that shows why policy wording matters
IRDAI's Master Circular on Life Insurance Products, 2024 includes provisions for pure-risk products. The following is a regulatory design point, not a promise that every policy provides the feature.
| Circular condition | Specified point | Reader takeaway |
|---|---|---|
| Completed policy years for a pure-risk product | Three completed policy years | After this point, the circular says a policyholder may be given a premium-reduction option, subject to the insurer's product terms. |
| Maximum stated reduction | Up to 50% of the original annualised premium | Minimum product limits, revised benefits and policy sustainability still apply; check the actual policy wording before acting. |
Keep the policy usable when it is needed
IRDAI's consumer guidance on buying insurance asks buyers to evaluate affordability, seek complete information on the scope of cover and exclusions, understand commitments and read the policy document. A practical annual review can include:
- Confirm the nominee and family contact details on record.
- Check premium due dates and whether the premium remains affordable.
- Keep the policy schedule, proposal details and claim contact route where the family can find them.
- Revisit coverage after a major change in income, debt, dependants or employer-provided benefits.
- Ask the insurer or a licensed professional to explain any wording that is not understood before changing or stopping a policy.
What the visual framework shows
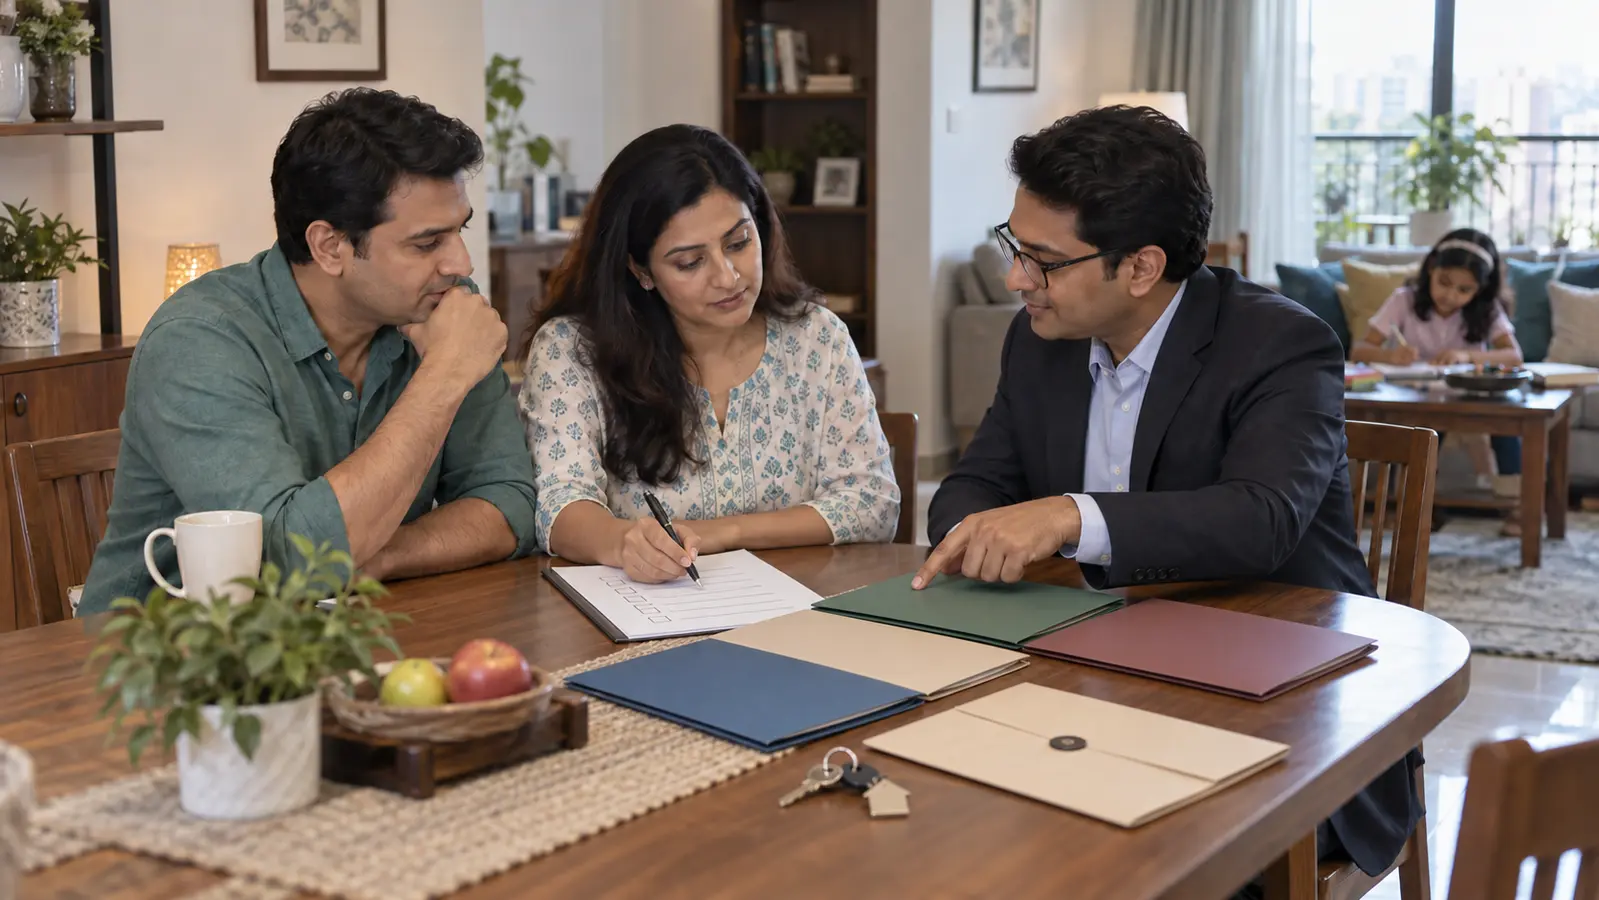
The visual separates the review into income, household obligations, policy documents and family access to records. The keyring and document envelope underline an operational point: a policy can only support a family effectively when the relevant records, nominee details and insurer contact path are maintained.
When policy service needs escalation
Keep written records of the issue and first use the insurer's grievance redressal channel. IRDAI's Bima Bharosa guidance states that policyholders should register grievances with the insurer first; the portal offers centralised online access for policyholder complaints.
Source Links
- IRDAI Introduction to Insurance
- IRDAI Master Circular on Life Insurance Products, 2024
- IRDAI consumer guidance on buying insurance
- IRDAI Bima Bharosa grievance guidance
Disclaimer
This article is for investor education only and is not insurance advice, a recommendation, an offer or a solicitation. Insurance is subject to policy terms, conditions, exclusions, underwriting and suitability. Read the policy document carefully, and obtain advice from a licensed insurance professional or other qualified adviser where appropriate.
Reviewed by Abhipra Research / Compliance Team.