Debt Allocation For Equity Investors: Why Stability Needs A Place In The Plan
Equity investors often focus on how much upside a portfolio can capture. That matters, but it is not the whole plan. A portfolio also needs money that can handle near-term goals, emergency needs and market drawdowns without forcing equity sales at the wrong time.
That is where debt allocation becomes important. It is not meant to compete with equity for long-term growth. It is meant to give the portfolio structure, liquidity and emotional discipline when markets are volatile.
Debt Is The Portfolio's Stability Layer
SEBI's investor education material explains diversification as spreading investments across different asset classes, and asset allocation as distributing capital based on goals, risk tolerance, time horizon and market outlook. It also reminds investors to match the investment type with the investment horizon and avoid volatile or illiquid investments when money is needed in the near future.
For an equity investor, debt allocation can serve four practical functions:
- It can fund short-term goals without depending on equity-market levels.
- It can reduce the need to redeem equities during drawdowns.
- It can support periodic rebalancing back into equities after sharp market falls.
- It can separate emergency money from long-term growth money.
The point is not to remove risk. Debt products have their own risks. The point is to choose the right kind of risk for the right time horizon.
Current Data Shows Debt Is Not A Side Topic
The July 2026 AMFI monthly report shows that debt-oriented mutual fund categories remained a large part of the investment landscape. Open-ended income and debt-oriented schemes recorded net inflows of about Rs 1,87,511 crore in July 2026 and net assets of about Rs 19,33,342 crore at month end. Equity-oriented schemes were larger by assets, but debt flows were material in that month.
| Category | Net inflow in July 2026 | Net assets at July 31, 2026 | Investor takeaway |
|---|---|---|---|
| Income/debt-oriented schemes | Rs 1,87,511 crore | Rs 19,33,342 crore | Debt allocation is a mainstream portfolio component, especially for liquidity and goal matching. |
| Growth/equity-oriented schemes | Rs 24,697 crore | Rs 38,36,192 crore | Equity remains the growth engine, but it needs a time horizon long enough to absorb volatility. |
| Hybrid schemes | Rs 11,491 crore | Rs 11,67,551 crore | Hybrid products show that many investors prefer managed equity-debt combinations. |
| Total open-ended schemes | Rs 2,36,595 crore | Rs 85,59,041 crore | Investor flows across asset classes can change sharply from month to month. |
The RBI's August 2026 rate context also matters. The RBI website showed the policy repo rate at 5.25%, the Standing Deposit Facility rate at 5.00% and the Marginal Standing Facility rate at 5.50% around the August policy period. Debt prices and yields respond to interest-rate expectations, liquidity and credit conditions, so debt allocation should be reviewed rather than treated as a fixed deposit substitute.
Match Debt Type To Time Horizon
AMFI describes debt funds as schemes that primarily invest in bonds or other debt securities, including government securities, debentures, commercial paper and certificates of deposit. It also explains that debt categories can be based on tenor, issuer type and fund-management strategy.
That means "debt" is not one product. An equity investor should separate the debt bucket by purpose.
| Investor need | Typical time horizon | Debt role to evaluate | Main risk to check |
|---|---|---|---|
| Emergency reserve | Immediate to 6 months | Savings account, sweep facility, overnight or liquid-oriented options after suitability review. | Liquidity, exit load, credit quality and settlement timing. |
| Known short-term goal | 6 months to 3 years | Low-duration or short-duration exposure, bank deposits, or other goal-matched instruments. | Interest-rate movement, credit risk and premature-withdrawal cost. |
| Portfolio stabilizer | 3 years and above | High-quality debt allocation that can be rebalanced against equities. | Duration risk, reinvestment risk and tax efficiency. |
| Income planning | Ongoing | A ladder of suitable instruments rather than one concentrated product. | Cash-flow mismatch, tax treatment and concentration in one issuer or category. |
Three Decisions Matter More Than A Single Percentage
An investor can ask, "How much debt should I hold?" A better process is to answer three questions first.
1. What Money Must Not Depend On Equity Markets?
Any money required for emergency needs, school fees, business commitments, loan obligations, home purchase timelines or near-term retirement withdrawals should not be hostage to equity-market levels. This is the first layer of debt or cash-like allocation.
2. What Equity Drawdown Can The Investor Tolerate?
An investor with 90% equity exposure should expect larger portfolio swings than one with 60% equity exposure. The debt portion should be sized so that the investor can stay invested through volatility without making panic redemptions.
3. What Rebalancing Rule Will Be Followed?
Debt allocation becomes useful when it is linked to a rule. For example, if equities rise sharply and exceed the planned range, part of the gains may be shifted to debt. If equities fall sharply and debt becomes overweight, part of the debt allocation may support buying equities back to plan. This is a discipline mechanism, not a market-timing promise.
Debt Funds Are Not Risk-Free
AMFI's risk education material states that mutual fund schemes are not guaranteed or assured-return products. It highlights risks such as liquidity risk, default risk, market risk and interest-rate risk. For fixed-income securities, it also explains the inverse relationship between interest rates and bond prices: when rates rise, prices of existing fixed-income securities generally fall, and when rates decline, such prices generally rise.
Debt allocation should therefore be reviewed on these points:
- Credit quality of the portfolio.
- Average maturity and duration.
- Concentration by issuer or sector.
- Liquidity and exit load.
- Expense ratio and tracking of stated strategy.
- Tax treatment under current law.
The tax point is important. The Income Tax Department's Section 50AA page states that gains on specified mutual funds acquired on or after April 1, 2023 are treated as capital gains from a short-term capital asset. AMFI's tax education page notes that from FY 2025-26, the specified mutual fund definition focuses on funds investing more than 65% in debt and money-market instruments, or funds investing 65% or more in such funds. Investors should confirm tax impact with a qualified adviser before choosing products.
What The Visual Framework Shows
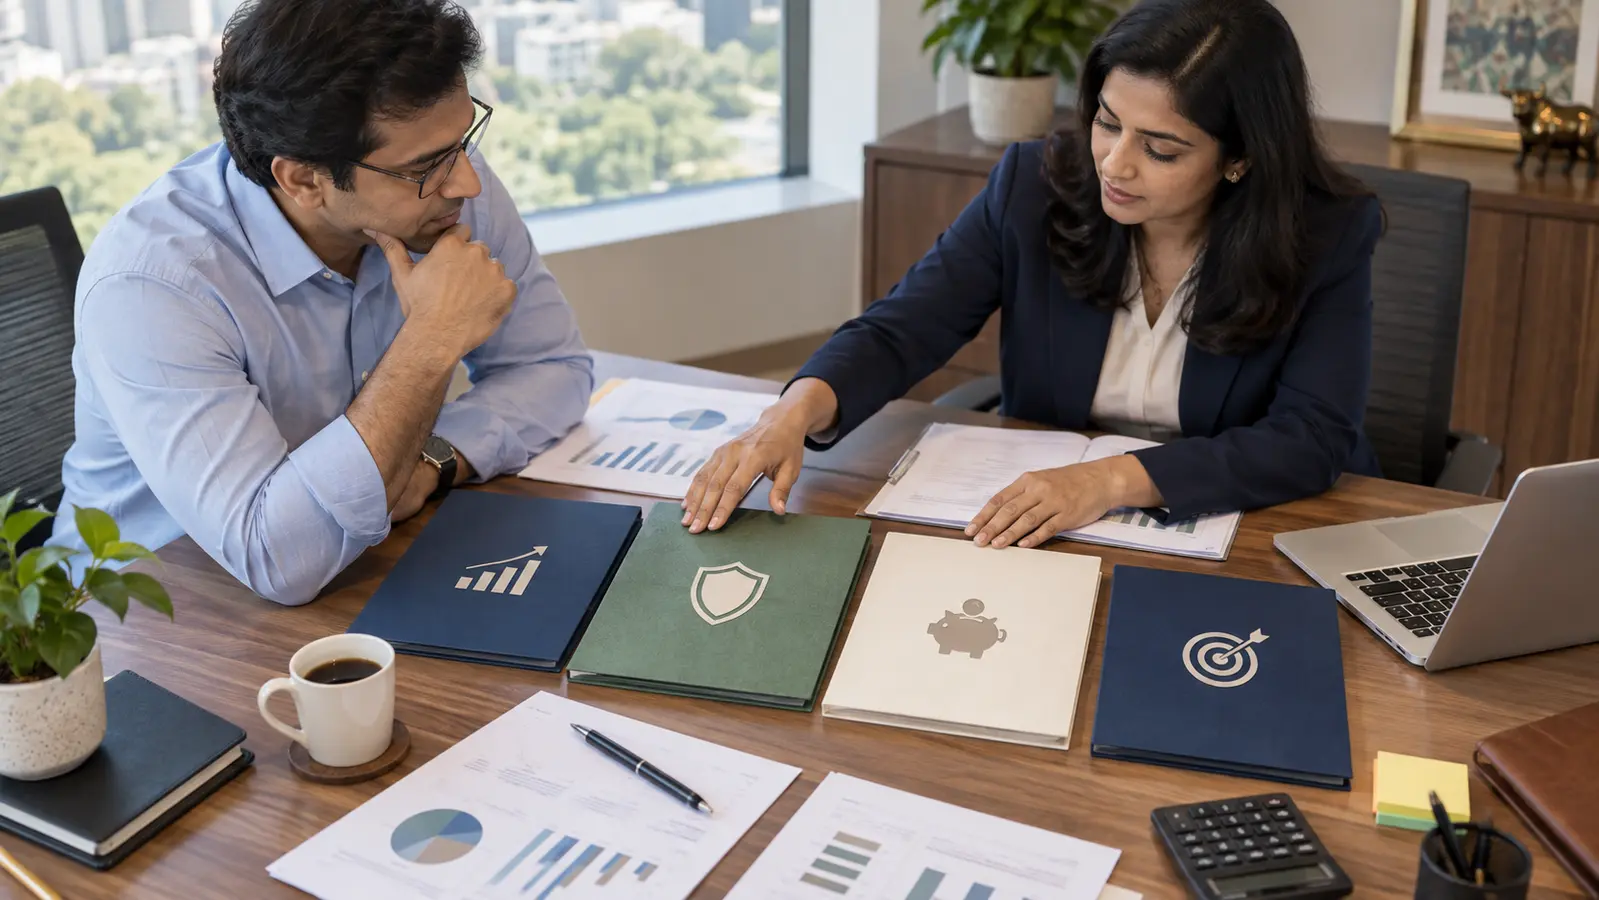
The supporting image shows a planner separating portfolio money into practical buckets: long-term growth, debt stability, emergency liquidity and goal-based money. The visual point is that debt allocation is not an afterthought. It is part of the operating system that helps an equity investor stay disciplined.
Investor Checklist
Before changing debt allocation, review these questions:
- Is the emergency fund separate from investment money?
- Are goals due within three years protected from equity volatility?
- Is the equity allocation realistic for the investor's drawdown tolerance?
- Does the debt bucket match the time horizon, liquidity need and tax situation?
- Is rebalancing written down as a rule, not decided during market stress?
- Has the product's credit risk, duration risk, expense and exit load been reviewed?
Final View
Equity builds long-term growth potential, but debt helps the investor stay with the plan. The right debt allocation is not about being conservative for its own sake. It is about making sure that short-term needs, liquidity and rebalancing discipline are not dependent on equity markets behaving well at the exact time money is needed.
For equity investors, debt is best treated as a planned stability layer: high enough to protect near-term goals and behaviour, but not so high that it weakens the long-term growth plan.
Source Links
- SEBI Investor Website: Factors Before Investing
- SEBI Investor Website: Investment Risk Management
- AMFI: Categorization of Mutual Fund Schemes
- AMFI: Risks in Mutual Funds
- AMFI: Monthly Reports Archive
- AMFI: July 2026 Monthly Report Workbook
- RBI: August 2026 Rate And Monetary Policy Context
- Income Tax Department: Section 50AA
- AMFI: Tax Regime for Mutual Funds
Reviewed by: Abhipra Wealth Planning Desk
Disclaimer: This article is for investor education only and is not investment, tax, legal or portfolio advice. Debt products, mutual funds and equity investments carry risks, and taxation can change. Please consult a qualified adviser before making investment decisions.